If you are planning to buy a home, how to get pre approved for a home loan is one of the first questions worth answering. A mortgage preapproval gives you a lender-reviewed view of your potential borrowing range before you make an offer. It can clarify a realistic budget, help you compare loan choices, and signal to sellers that you have started the financing process. It is not final approval, but it gives you a far better starting point than shopping with only a rough estimate.
Buyers often search how to get pre approved for a house because they want to move quickly once they find the right property. Start by checking your monthly budget, credit report, savings, and current debt. Then contact more than one lender and ask what its preapproval process requires. The Consumer Financial Protection Bureau recommends comparing multiple lenders; a preapproval helps you compare loan options and pricing while you decide which lender fits your needs.
What Is Getting Pre Approved for a Mortgage
To understand what is getting pre approved for a mortgage, think of it as a lender’s preliminary review of your financial picture. The lender evaluates information such as income, employment, assets, debts, and credit history, then may issue a letter with an estimated loan amount and conditions. The letter is useful when making an offer, but it does not eliminate later underwriting, appraisal, title, or property-related requirements.
The terms are not always used the same way. When you ask how can i get prequalified for a home loan, you may receive an estimate based largely on information you report. A preapproval often involves more documentation and credit review. Ask each lender exactly what it verified, whether the letter reflects a hard credit inquiry, and which conditions still need to be met. That makes it easier to compare like with like.
Mortgage Pre Approval Process and Documents
The mortgage pre approval process usually begins with a conversation or online application. You provide basic information about your income, employment, assets, debts, and the kind of home you expect to buy. The lender reviews your credit and asks for documents that support the information in your application. If you are asking how can i get pre approved for a home loan, begin by organizing these records before you apply.
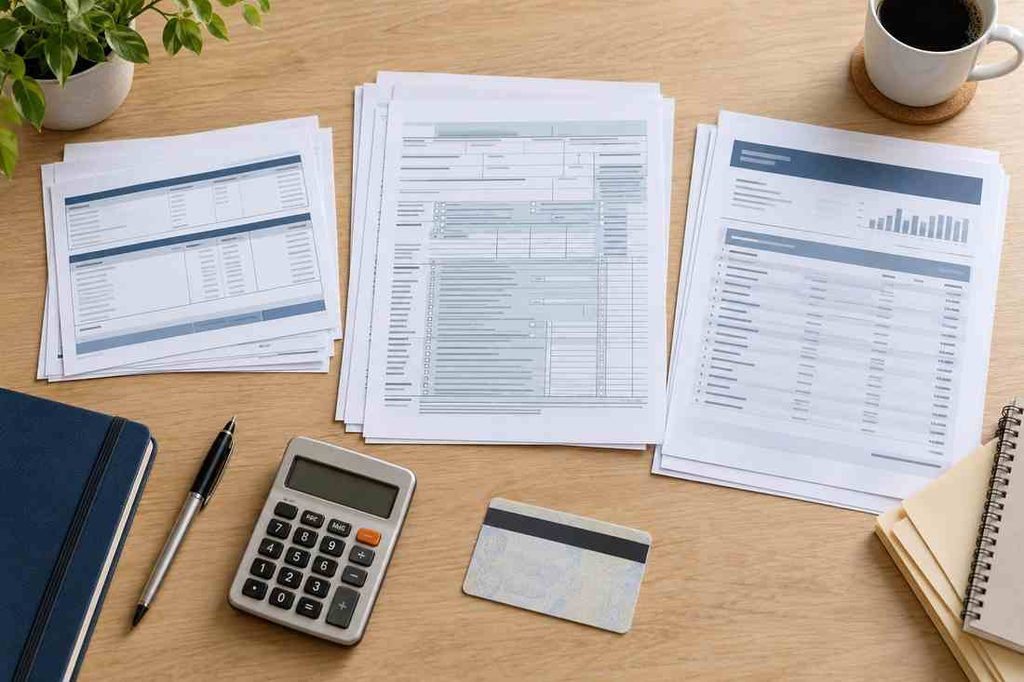
Most lenders request a government-issued ID, recent pay stubs, W-2s or tax returns, recent bank or investment statements, and information about current debts. Self-employed borrowers may need business returns, a profit-and-loss statement, or additional bank records. These are common parts of the review, but requirements vary by loan program and lender.
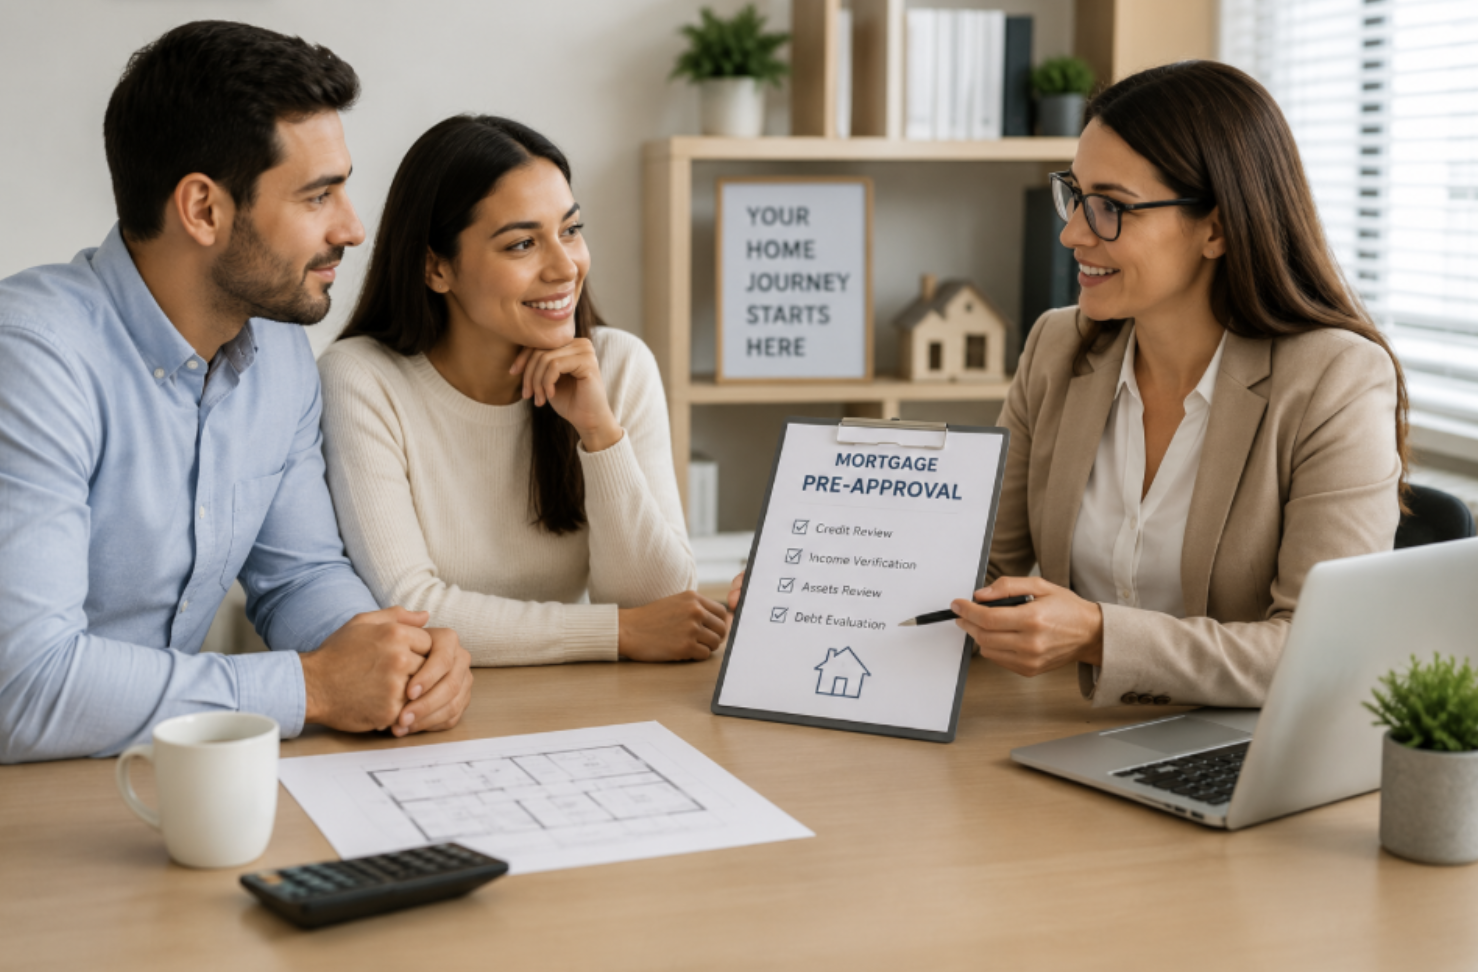
Those records show what goes into getting preapproved for a mortgage. Lenders generally evaluate whether your income is stable enough for the payment, how much debt you already carry, your available funds for closing and a down payment, and your credit profile. These are the core mortgage pre approval qualifications, though the exact standards depend on the loan type and lender. If you are asking what is needed to get prequalified for a home loan, start with a basic summary of your income, monthly obligations, cash available, and estimated home price. For a stronger preapproval, be prepared to document those details. Keeping your paperwork in one secure folder can reduce back-and-forth and help you respond quickly if the lender has a question.
Steps to Get Preapproved for a Mortgage
The following steps to get preapproved for a mortgage give you a practical checklist:
- Review your budget and decide on a comfortable monthly payment, not only the highest amount a lender might approve.
- Check your credit reports for errors and avoid opening new accounts or taking on major debt before applying.
- Gather pay stubs, tax documents, statements, identification, and any information about gift funds or variable income.
- Contact at least three lenders, compare their questions, estimated terms, and service, and submit complete information.
- Read the letter carefully, ask about conditions and expiration, and keep your financial situation steady while home shopping.
These are the main steps for mortgage pre approval. Some borrowers pursue an underwritten pre approval, which may involve a deeper upfront review. It can be helpful in a competitive situation, but its meaning and documentation level vary by lender, so ask what the lender has actually reviewed.
People who search how to get preapproval for a home loan or how to get pre approval for a mortgage loan should remember that a complete application is more useful than an incomplete one. Give accurate information, disclose debts and expected changes, and ask before moving money between accounts. Large unexplained deposits or a new loan payment can create follow-up questions.
When to Get Preapproved for a Mortgage
The best answer to when to get preapproved for a mortgage is usually when you are serious about shopping and could make an offer within the letter’s validity period. The CFPB notes that preapproval letters can expire, often in 30 to 60 days, although each lender sets its own terms. Getting one early can also reveal credit or documentation issues before a specific home is involved.
So, should i get pre approved for a mortgage before looking? In most cases, yes, especially if you would be ready to act on the right home. Similarly, should you get pre approved before looking for a home becomes less of a question when sellers or real estate agents expect a letter with an offer. Preapproval helps you search within a supportable price range, but it should never replace your own affordability review.
For buyers asking how early should i get pre approved for a mortgage, start with a lender conversation as you begin financial planning, then request the formal letter when you are preparing to tour homes seriously. If you are on a tighter schedule and wonder how to get pre approved for a home loan fast, have all your documents ready and respond promptly. The actual timing depends on how complete your file is and whether the lender needs clarification. There is no universal answer to how long to get pre approved for mortgage or how long to get a mortgage pre approval. A straightforward file may move quickly, while self-employment, irregular income, gift funds, or recent financial changes can require more review. Ask your lender for an expected timeline and an explanation of what could delay it.
Use Your Preapproval to Shop Smarter
When you are deciding how to get preapproval for a mortgage, treat the letter as a planning and comparison tool, not a blank check. Use it to evaluate a full monthly housing cost, including principal, interest, taxes, insurance, possible mortgage insurance, and maintenance. A lower purchase price may still be a better fit if it protects your savings and long-term goals.
Preapproval also does not lock you into a lender. Ask about rates, fees, program options, communication, and next steps before making your decision. Avoid opening a new credit account, changing jobs, taking on a new car payment, or moving money without asking how it could affect the file. A careful approach helps protect the progress you have made.
Quick Preapproval Questions
If you are wondering how can i get preapproved for a mortgage, a good first move is to contact several lenders and ask for their document checklist, estimated timeline, and explanation of any credit review. Complete answers are better than guesses, so use the same accurate financial information with each lender.
Another common question is should i get pre approved for a mortgage. Preapproval is especially useful when you are close to touring homes or making offers because it helps keep your search aligned with a realistic price range.
For buyers who want a precise answer to what is needed to get prequalified for a home loan, prepare a summary of income, assets, monthly debts, and your desired price range. A lender can tell you whether that initial discussion is a prequalification or whether more documents are needed for a preapproval.