If you’re saving for your first home, the down payment is probably the number that worries you most. A lot of people think they need 20% saved before they can buy. That’s not true for most buyers.
This guide breaks down the first time home buyer down payment Utah buyers can expect, how your credit score fits in, and the programs that can help you cover the cost.
How Much Is the Average Down Payment on a House?
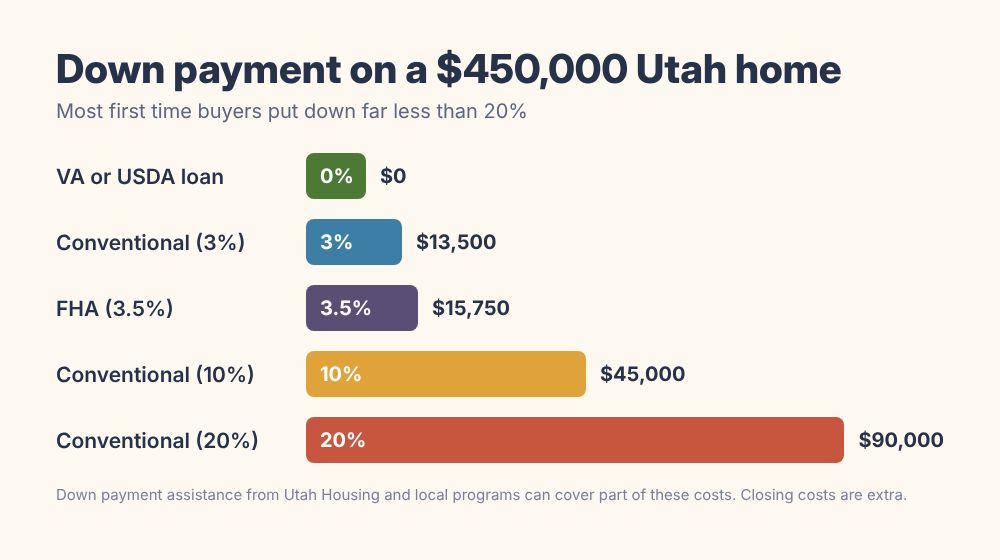
The average down payment on a house for first-time buyers has been around 9% to 10% in recent National Association of Realtors surveys, and plenty of buyers put down even less.
The right down payment for house purchases depends on your loan type, your credit, and the price of the home. Here’s how it adds up on a $450,000 home in Utah.
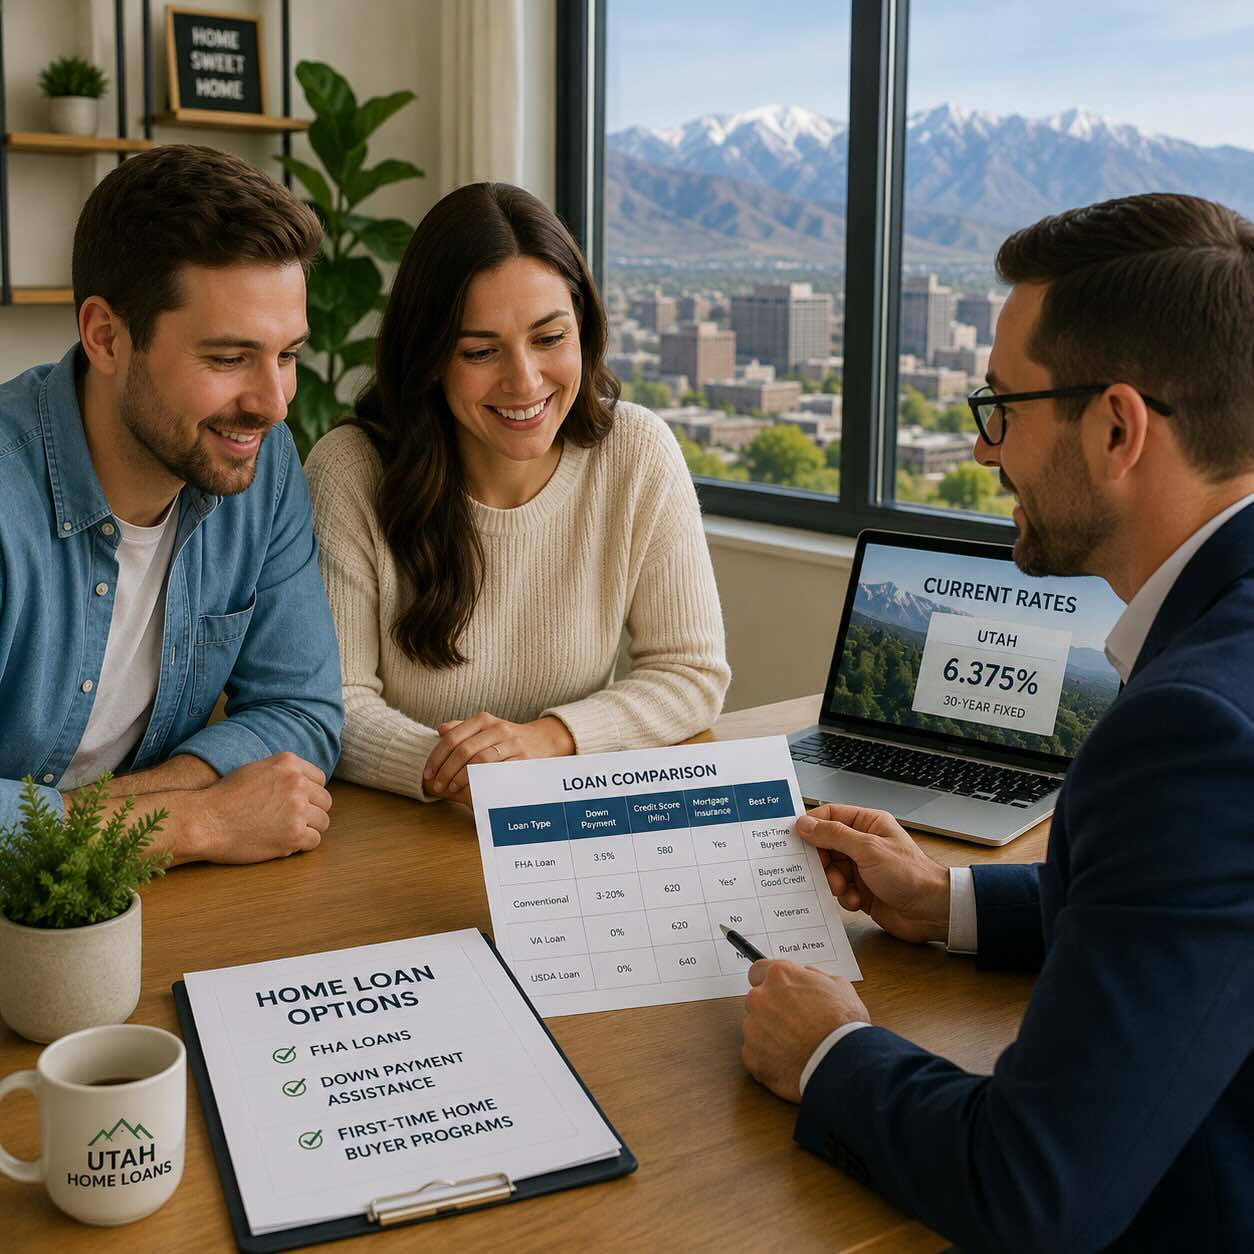
Best First Time Home Buyer Loans for a Low Down Payment
The best first time home buyer loans are the ones that let you buy without draining your savings. Here are the main first time home buyer loans to know about.
FHA loan first time home buyer option: An FHA loan is backed by the federal government. You can put down as little as 3.5% if your credit score is 580 or higher. That’s why the FHA first time home buyer route is so popular. The tradeoff is that you pay mortgage insurance. Learn more on our FHA loans page.
Conventional loans: Some conventional programs let first-time buyers put down just 3%. If you put down less than 20%, you’ll pay private mortgage insurance, but you can usually remove it once you have enough equity.
First time home buyer loans with zero down: If you’re a veteran or service member, a VA loan may let you buy with nothing down. USDA loans also offer a no down payment first time home buyer option for homes in eligible rural parts of Utah, and there are more of those areas than most people think.
No matter which first time home owners loan you choose, compare the total monthly payment, not just the down payment. A smaller down payment means a bigger loan and a higher monthly cost.
Credit Score Needed to Buy a House in Utah
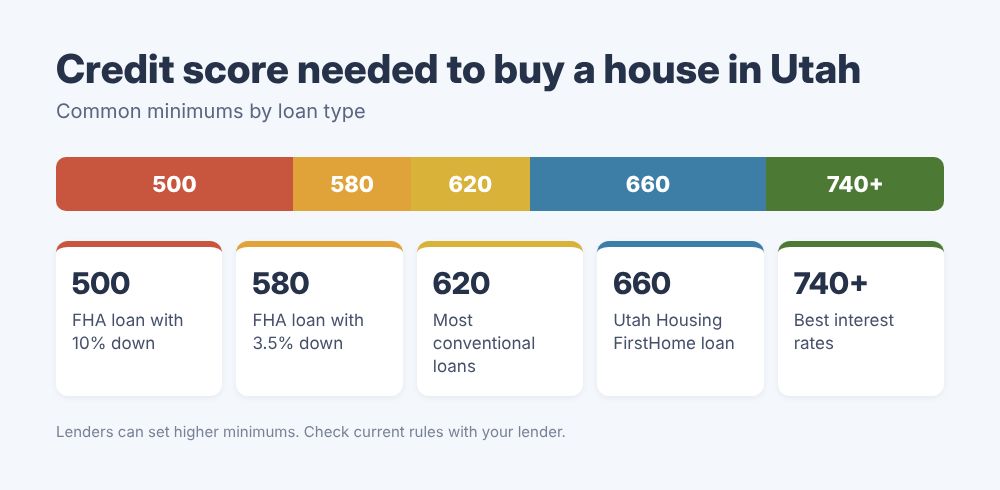
Your credit score to buy a house affects which loans you qualify for and the rate you get. The credit score needed to buy a house in Utah depends on the loan:
- FHA: 580 with 3.5% down, or 500 with 10% down
- Conventional: Usually 620
- Utah Housing FirstHome loan: Usually 660
- Best rates: Often 740 and up
Keep in mind that the minimum credit score to buy a house is set by the loan program, but lenders can ask for more.
A higher score can also lower your first time home buyer interest rate. Even a small rate difference can add up to thousands of dollars over 30 years.
First Time Home Buyer Programs Utah Residents Can Use
You don’t have to cover your down payment alone. These first time home buyer programs Utah buyers can use are worth checking out.
Statewide first time home buyer programs are run by Utah Housing Corporation, and some cities add their own.
Utah Housing FirstHome loan: This first time home buyer mortgage comes with a fixed rate and the option of down payment assistance through a second loan. You’ll usually need to take a short homebuyer education course.
Utah Housing Score loan: This one is for buyers with credit scores in the 620s and lower 600s who don’t meet FirstHome’s credit requirement yet.
The $20,000 First-Time Homebuyer Assistance Program: The state offers up to $20,000 toward a down payment, closing costs, or a lower rate on a newly built home priced at $450,000 or less. It’s a loan you pay back when you sell or refinance, and funding is limited. A 2026 bill to open it up to existing homes did not pass, so for now it still only covers new construction.
City programs: Salt Lake City, Provo, Ogden, and other cities have run their own down payment help for buyers who meet income limits.
Rules change every year, so check the latest details on first time home buyer programs Utah 2026 before you apply. Our complete guide to first time home buyer programs in Utah goes deeper on each one.
First Time Home Buyer Requirements Utah Lenders Look For
Most first time home buyer requirements Utah lenders use come down to four things:
- A credit score that meets your loan’s minimum.
- Steady income, usually with two years of work history.
- A debt-to-income ratio that fits the loan. See our post on debt-to-income ratio for mortgage approval.
- Enough money for the down payment and closing costs, from savings, gifts, or assistance.
How to Apply for a First Time Home Loan
Here’s how to apply for a first time home loan step by step.
Start with a first time home buyer calculator. A first time home buyer loan calculator shows you how your down payment, rate, and loan type change your monthly payment. Try our mortgage qualification tools.
Next, get your first time home buyer pre approval. A pre-approval tells you how much you can borrow and shows sellers you’re serious. Our mortgage pre-approval guide walks you through it.
Then compare first time home buyer lenders. The best mortgage lenders for first time home buyers work with Utah Housing programs, explain your options clearly, and don’t bury fees in the fine print.
Get quotes from at least three. For more on federal loan options, see HUD’s home buying page.
The Bottom Line
You don’t need 20% down to buy your first home in Utah. With the right loan, a solid credit score, and help from state and local programs, your first home might be closer than you think.
Start with a budget, get pre-approved, and talk to a lender who knows Utah’s programs.