Buying your first home is exciting, but saving for a down payment, understanding mortgage requirements, and paying closing costs can feel overwhelming. If you are a first time home buyer Utah resident, there are several financing paths worth exploring. This guide explains Utah first time home buyer programs, loan types, credit questions, and the practical steps from budgeting to closing. The goal is to help you ask better questions before committing to a mortgage, not to promise that every buyer qualifies for assistance.
First Time Home Buyer Programs Utah: Where to Start
People searching for first time home buyer programs utah often assume there is one statewide grant that covers every home. In reality, different programs have different rules. Utah Housing Corporation works with participating lenders and offers mortgage and assistance options. One state-funded first-time buyer program was established to help eligible purchasers of qualifying newly built homes with up to $20,000. Its assistance is an interest-free loan, not free money: repayment may be triggered by sale or refinance. Buyers should check the latest rules and whether funds remain available before shopping around a benefit that may not apply to their purchase.
Searches for first time home buyer grants utah can also lead to other programs, including lender-accessible grants that have separate income, occupancy, education, and retention rules. Always distinguish a grant from a repayable second mortgage. A participating lender can explain what is currently offered and which combinations are permitted.
Down Payment Assistance Utah: Compare the Real Costs
The phrase down payment assistance Utah covers more than one type of help. Utah down payment assistance programs may provide a second loan that helps cover the cash needed at closing. Some assistance has a monthly payment, while other assistance may defer payment until a later event. These details matter because an affordable down payment today does not automatically mean the lowest lifetime borrowing cost.
For a first time home buyer down payment Utah budget, calculate the required cash from savings, any assistance, and the closing costs you must still pay. Ask the lender to show a side-by-side estimate with and without assistance, including the interest rate, monthly payment, second-loan balance, and any repayment trigger. Compare the amount of assistance with the extra interest or fees you might pay.
For example, suppose a buyer needs $12,000 for a down payment and $8,000 for closing costs. An assistance loan could reduce the cash needed up front, but it would still be debt if repayment is required. Ask for written terms before assuming the entire $20,000 is a gift.
First Time Home Buyer Requirements Utah: Credit and Income
A common question is the credit score to buy a house in Utah. There is no single score that works for every mortgage. Minimum credit score for mortgage Utah searches produce different answers because lenders, loan programs, and individual borrowers differ. For example, FHA financing may allow a 3.5% down payment with qualifying credit of at least 580 under FHA guidelines, while lower scores can require more down payment and a lender may apply stricter standards.
People researching first time home buyer programs with bad credit should start by checking credit reports, correcting errors, paying bills on time, and asking lenders which products they actually offer. A weaker score does not necessarily end the search, but it can change eligibility and pricing. In addition to credit, first time home buyer requirements Utah commonly include verifiable income, acceptable debt-to-income ratios, sufficient assets, and an eligible property. Assistance programs may add household-income, purchase-price, residency, or education conditions.
FHA, VA, USDA, and Conventional Loans in Utah
FHA loans for first time home buyers Utah can be attractive when savings are limited. FHA loan requirements Utah include occupancy, property, income, and underwriting standards, as well as mortgage insurance. FHA loan limits Utah depend on the county, property type, and year, so look up the current limit for the exact property rather than relying on an older blog post.
A VA home loan Utah option may allow eligible military borrowers to buy with no down payment and without monthly private mortgage insurance. VA loan requirements Utah include service-based eligibility and lender review of income, credit, and property conditions; a VA funding fee may apply unless the borrower is exempt. A USDA home loan Utah option may also offer zero-down financing to qualifying borrowers buying in eligible areas, subject to income and property rules.
Conventional loan requirements Utah vary by lender and product. Some qualifying conventional mortgages allow down payments as low as 3%, while mortgage insurance may apply below 20% down. Rather than assuming one loan is always best, compare the annual percentage rate, cash to close, total monthly payment, and long-term cost.
Mortgage Pre Approval Utah: A Step-by-Step Plan
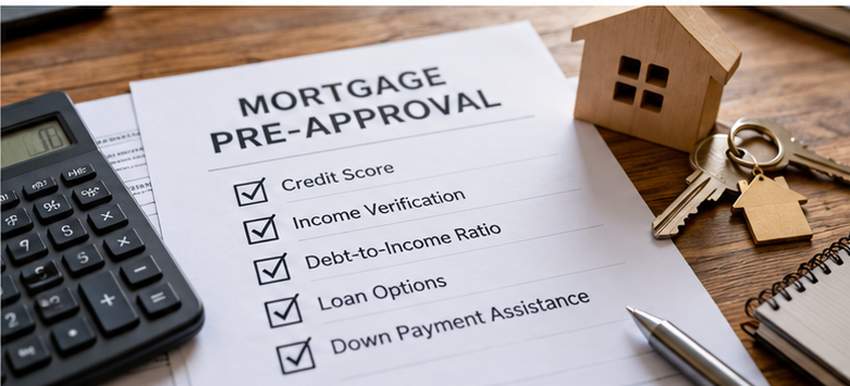
Wondering how to get pre approved for a mortgage in Utah? First, estimate a comfortable monthly housing budget. Next, collect recent pay statements, tax information when needed, bank statements, identification, and a list of current debts. Then contact a lender for mortgage pre approval Utah and ask what documents or credit checks are required. A preapproval is conditional, not a guarantee of final approval.
When asking how much house can I afford in Utah, do not use only the largest loan amount a lender offers. Include property taxes, homeowners insurance, homeowners association fees if applicable, utilities, repairs, and a savings cushion. This makes it easier to shop for a house that fits your actual life rather than just your maximum borrowing capacity.
Mortgage Closing Costs Utah and Mortgage Insurance
Budgeting for mortgage closing costs Utah is essential even when assistance reduces the down payment. The answer to how much are closing costs in Utah depends on the purchase price, loan, lender, title services, prepaid taxes, and insurance. A commonly cited planning range is roughly 2% to 5% of the loan amount, but your Loan Estimate will be more useful than a generic percentage.
Mortgage insurance cost Utah also depends on the loan type and borrower. Conventional private mortgage insurance and FHA mortgage insurance work differently, and VA loans do not require monthly mortgage insurance. Ask for the total estimated monthly payment and for an explanation of when, if ever, insurance can be removed.
How to Buy a House in Utah for the First Time
If you are searching how to buy a house in Utah for the first time, use this sequence: review your budget and credit, compare lenders and loan programs, request preapproval, confirm assistance eligibility, shop for an eligible property, make an offer, complete inspections and appraisal, and review your final closing disclosure before signing. A real estate agent and loan officer can help you coordinate deadlines.
Before applying, read the current Utah Housing Corporation program guidelines and ask whether the home you want qualifies. A new-construction-only assistance program will not help with an existing home, even if you otherwise meet income and credit standards. If you have questions, talk with a participating lender about both the first mortgage and any assistance loan. Understanding the full cost now can make your first purchase more sustainable later.
Your next step: request a written loan comparison from a Utah Housing participating lender, confirm program funding, and keep enough savings for moving expenses and unexpected repairs. Assistance is most useful when the complete mortgage remains affordable.