Buying a home or paying for home improvements can be exciting, but figuring out how to finance those expenses can feel overwhelming. Between interest rates, loan requirements, and monthly payments, there is a lot to consider before making a decision. Two options worth understanding are home equity lines of credit (HELOCs) and VA home loans. Although they serve different purposes, both can help eligible borrowers manage their housing expenses. Understanding how these loans work can help you compare options and make a decision that fits your financial goals.
Understanding HELOCs and Current Interest Rates
A home equity line of credit, commonly called a HELOC, allows homeowners to borrow against the equity they have built in their homes. Unlike a traditional home equity loan, a HELOC generally allows borrowers to access funds as needed, up to an approved credit limit. This flexibility can make it useful for renovations, repairs, and other major expenses.
When researching HELOC loan rates, it is important to understand how interest rates affect borrowing costs. Comparing HELOC loan rates and terms can help homeowners evaluate repayment periods, fees, variable interest rates, and other conditions before applying.
Homeowners researching HELOC loan rates right now or comparing HELOC rates today should review current offers from multiple lenders. Rates can change with market conditions, and the rate a borrower receives depends on factors such as credit history, income, and available home equity.
Using HELOC Calculators to Estimate Payments
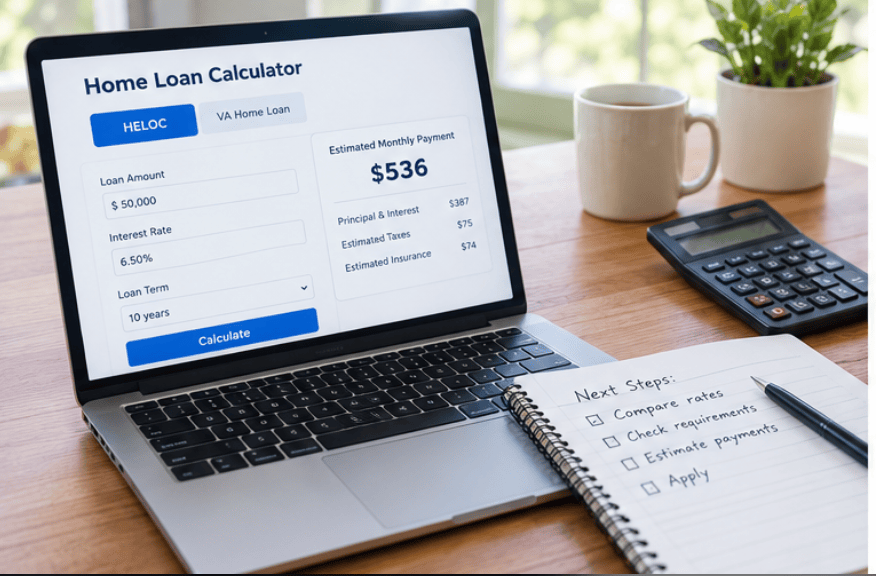
Online tools can make comparing loan options easier. A HELOC loan rates calculator can help homeowners explore how different interest rates and borrowing amounts affect their costs. Similarly, a HELOC payment calculator can estimate payments based on the amount borrowed and the applicable interest rate.
Some homeowners may also use a HELOC interest only calculator to understand payment structures during an interest-only period. However, interest-only payments generally do not reduce the principal balance, and payments may increase when the repayment period begins.
For additional guidance, visit our mortgage calculator page to explore estimated mortgage payments and housing costs.
HELOC Requirements and Finding the Right Loan
Before applying, homeowners should understand HELOC requirements. Lenders typically consider credit history, income, existing debt, and the amount of equity available in the property. Researching HELOC rates by credit score can also help borrowers understand how their credit profile may affect the offers they receive.
For those searching for best HELOC rates near me, comparing banks, credit unions, and other lenders is a useful starting point. Look beyond the advertised rate and consider fees, repayment flexibility, and customer service.
A common question is whether a HELOC for home improvement is a good idea. A HELOC can provide flexible access to funds for projects such as kitchen renovations, roof repairs, or bathroom upgrades. However, because the home generally serves as collateral, borrowers should make sure they can afford the payments before taking on additional debt.
Homeowners may also wonder whether HELOC interest is tax deductible. Whether a HELOC tax deductible benefit applies depends on the circumstances, including how the borrowed funds are used and applicable tax rules. The IRS guidance on home mortgage interest provides more information about relevant requirements. Consult a qualified tax professional for advice about your situation.
It is also helpful to understand HELOC vs home equity loan differences. A HELOC typically provides revolving access to funds, while a home equity loan generally provides a lump sum with scheduled repayments. The right choice depends on the project, budget, and available loan terms.
Understanding VA Home Loans
VA home loans are designed to help eligible veterans, active-duty service members, and certain surviving spouses purchase, build, or refinance a home. Because these loans are backed by the U.S. Department of Veterans Affairs, they have program features that differ from conventional mortgages.
A VA home loan calculator can help prospective buyers estimate monthly payments before applying. Using a VA home loan calculator free of charge is a practical way to compare different home prices, down payments, interest rates, and loan terms.
Borrowers may also search for a VA home loan calculator USAA when researching tools offered by a particular financial institution. Regardless of the calculator, check whether the estimate includes property taxes, homeowners insurance, and other housing expenses.
If you are wondering VA home loan calculator how much can I afford, start by reviewing your monthly income, existing debt, savings, and other expenses. A calculator provides an estimate, but it cannot determine your complete financial readiness to buy a home.
VA Home Loan Requirements, Rates, and Closing Costs
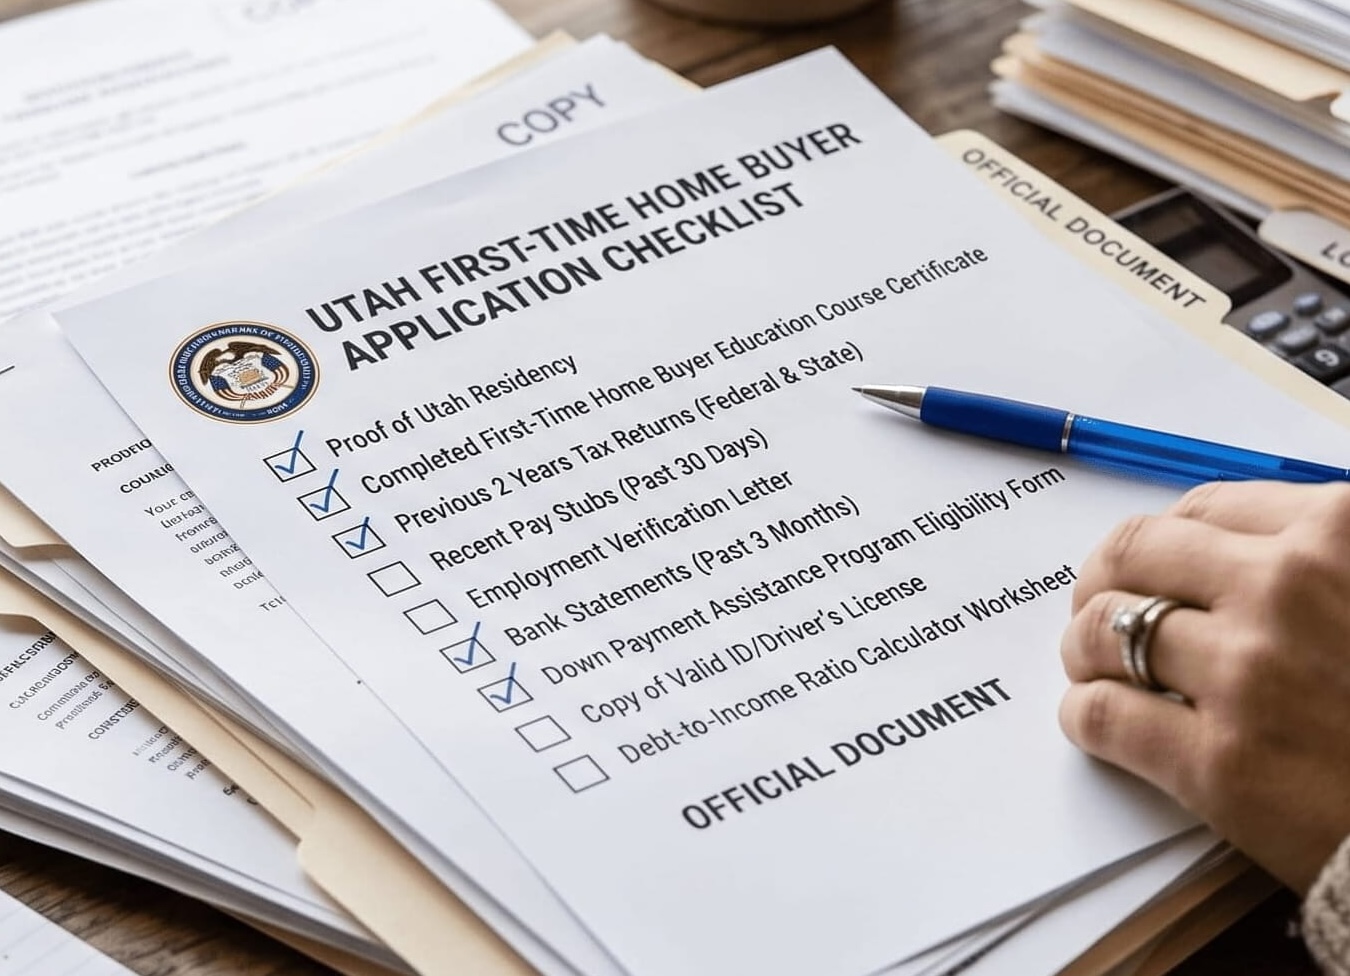
Before applying, review VA home loan requirements to understand the eligibility rules and documentation involved. The VA provides official guidance on eligibility and the Certificate of Eligibility through its VA home loan benefits page.
A VA home loan eligibility calculator may help you begin exploring your options, but an online estimate is not an official eligibility determination. Confirm your eligibility through the VA or a participating lender.
Comparing VA home loan rates today can help you understand available offers. However, rates vary by lender, market conditions, credit profile, and loan details. Comparing multiple offers is a good way to evaluate your options.
Buyers should also budget for VA home loan closing costs, which may include appraisal, title, and other transaction-related expenses. Some costs may be paid by the seller depending on the agreement and applicable rules.
Another topic to research is VA home loan limits 2026. Eligible borrowers with full VA loan entitlement generally are not subject to a VA-imposed loan limit, although lenders still evaluate affordability and repayment ability. Borrowers with reduced entitlement may face different considerations. Check the VA’s official guidance for the rules applicable to your situation.
Refinancing With a VA Home Loan
Homeowners who already have a VA loan may want to explore refinancing if market conditions or their financial circumstances have changed. Comparing VA home loan refinance rates can help borrowers assess whether refinancing may be worthwhile.
The VA streamline refinance calculator can help with preliminary estimates for an eligible Interest Rate Reduction Refinance Loan (IRRRL). However, borrowers should consider closing costs, eligibility requirements, and long-term savings rather than focusing only on a lower monthly payment. Review the VA’s official refinancing guidance before making a decision.
Making an Informed Mortgage Decision
Whether you are considering a HELOC for renovations or a VA home loan to purchase a home, researching your options is an important first step. Compare interest rates, understand eligibility requirements, and estimate payments before committing to a loan.
Explore our mortgage loan resources to learn more about home financing options. You can also speak with a qualified lender to understand which products fit your circumstances.
Ultimately, the best financing option depends on your goals, budget, and eligibility. Taking time to compare loan terms and understand the potential risks can help you make a more confident decision about your next housing move.