Choosing a home loan is about more than finding a low advertised rate. The right mortgage lender should explain your options clearly, provide an estimate you can understand, and offer a loan that works with your budget and timeline. If you are buying your first home in Utah or considering a new loan on a home you already own, comparing offers can help you make a more confident decision. Start by looking at the full cost of borrowing—not just the headline number.
Compare Mortgage Rates and the Full Cost of a Loan
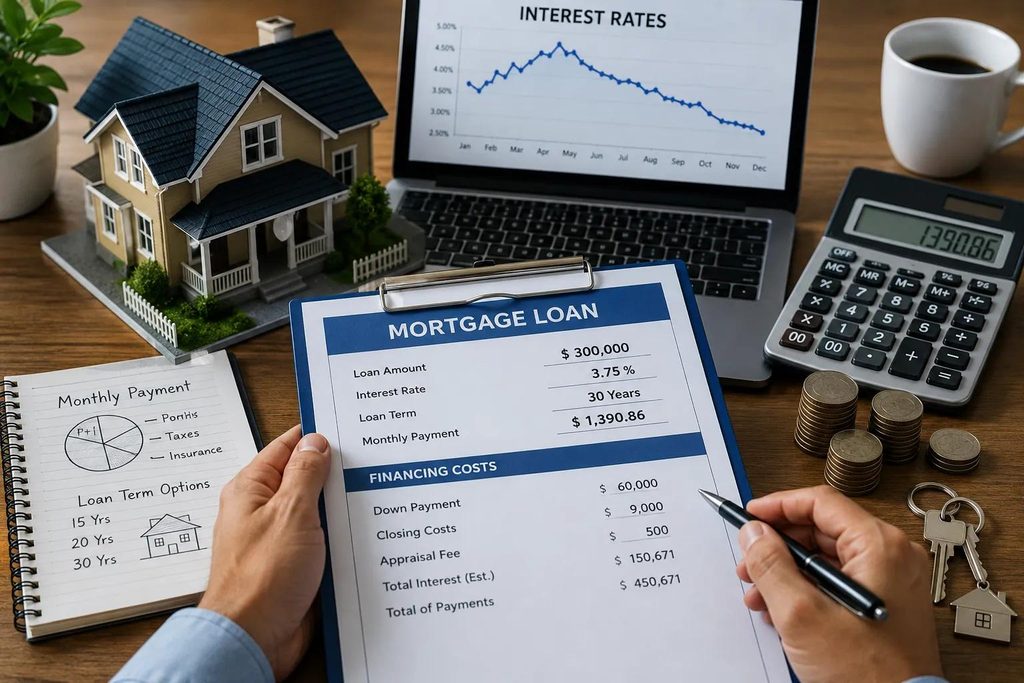
When researching mortgage rates, you will see a range of offers and rate tables online. Mortgage rates today and current mortgage rates can change, and the rate you receive may depend on your credit history, down payment, loan type, property, and other factors. The advertised best mortgage rates are not necessarily available to every borrower. Instead of relying on a general rate, ask several lenders for a written mortgage quote using the same loan amount, down payment, loan term, and loan type.
Compare the interest rate alongside the annual percentage rate (APR), origination charges, discount points, lender credits, estimated closing costs, and total monthly payment. A lower interest rate may require you to pay more upfront, while a loan with fewer upfront costs may have a higher payment. The Consumer Financial Protection Bureau explains how to review and compare standardized Loan Estimates at https://www.consumerfinance.gov/owning-a-home/compare/. Use the same assumptions for each quote so that you are comparing similar offers.
Use a Mortgage Calculator Before You Apply
A mortgage calculator or home loan calculator can help you estimate principal and interest based on the purchase price, down payment, interest rate, and repayment term. It is a useful first step when deciding what monthly payment may fit your finances. However, the amount you can afford is not always the same as the amount a lender will approve. A realistic housing budget should also consider property taxes, homeowners insurance, mortgage insurance, HOA dues, utilities, maintenance, and other monthly obligations.
Before you apply for a mortgage, review your income, existing debts, savings, and credit. Ask lenders which documents they need and how long their process typically takes. A mortgage pre approval can provide an initial estimate of how much you may be able to borrow, which can help guide your home search. It is not a final approval or a guarantee that the loan will close; the lender still needs to verify your information and evaluate the property.
Evaluate Mortgage Lenders, Brokers, and Loan Programs
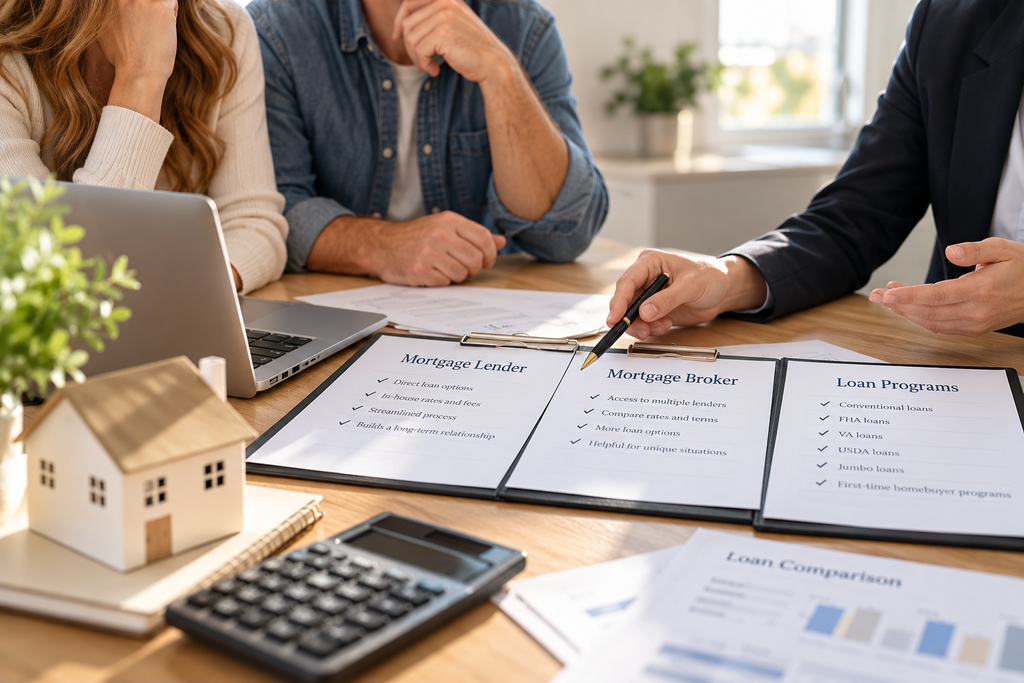
When comparing the best mortgage companies or best mortgage lenders, look beyond online rankings. Consider whether the lender answers questions promptly, explains fees in plain language, offers a loan program that fits your needs, and can reasonably meet your closing timeline. If you search for a mortgage broker near me, ask which lenders the broker works with, how the broker is compensated, and whether you will receive written estimates from more than one option. A broker can help you explore choices, but you should still compare the actual terms and costs yourself.
Different borrowers may need different home loans. Conventional loans may suit some buyers, while eligible service members, veterans, and qualifying surviving spouses may consider a VA home loan. A VA loan has program-specific eligibility and requirements, so ask a knowledgeable lender how they apply to your circumstances. A VA loan calculator may help estimate principal and interest, but the final payment can include other costs. If you are comparing VA loan rates, make sure the quotes use the same loan amount, term, and assumptions.
Understand Refinancing and Home Equity Options
If you already own a home, mortgage refinancing may be worth exploring when you want to change your interest rate, loan term, or other mortgage terms. A refinance home loan replaces your existing mortgage with a new one, so compare closing costs with the potential savings and consider how long you expect to stay in the home. A refinance calculator can provide an initial estimate, but the result depends on the information you enter and does not guarantee that refinancing will save you money.
A cash out refinance allows a homeowner to replace an existing mortgage with a larger loan and receive part of the equity as cash, subject to lender approval and loan terms. Because it can increase the amount owed against the home, compare the new payment, fees, interest over time, and your plans before deciding.
A home equity loan and a home equity line of credit are other ways eligible homeowners may borrow against equity. A home equity loan generally provides a lump sum, while a HELOC (also called a heloc) typically allows the borrower to draw funds under a revolving credit line. Compare home equity loan rates and HELOC rates, fees, draw and repayment periods, and whether the interest rate can change. A HELOC loan is secured by your home, so missed payments can put the property at risk. These products are different from a purchase mortgage and should be considered carefully.
Choose a Lender That Fits Your Situation
Some borrowers have specialized needs. A reverse mortgage calculator may provide an estimate for certain reverse mortgage options, but it does not replace a review of eligibility, fees, ongoing obligations, and independent counseling where applicable. Before choosing any loan, make sure you understand what the lender is offering and how the loan works over time. Tools and online estimates are helpful starting points, not substitutes for reviewing the official loan documents.
If you are planning to improve a property, home improvement loans may be another financing option to research. Compare the total cost, repayment period, and whether the loan is secured or unsecured. Do not assume that a home equity product, personal loan, and mortgage refinance have the same risks or costs. The right choice depends on your project, budget, credit, and how long you expect to keep the home.
A Simple Checklist Before You Commit
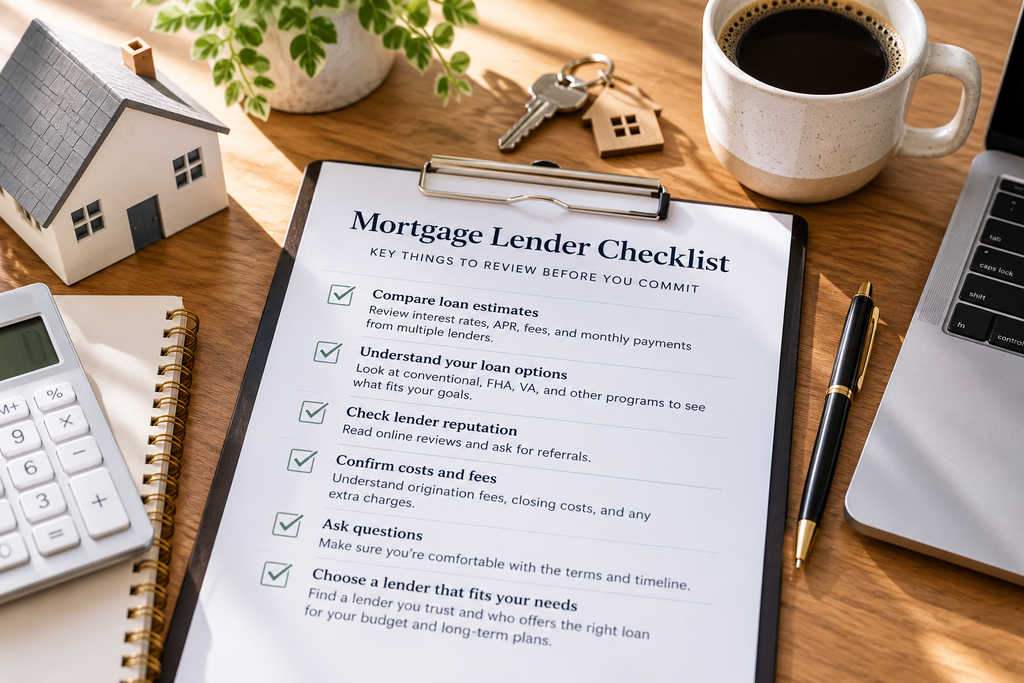
Before selecting a mortgage lender, request Loan Estimates from multiple lenders and check that each one reflects the same loan type, amount, term, and down payment. Compare the interest rate, APR, monthly payment, lender-controlled fees, lender credits, cash needed at closing, and estimated cost over time. Ask questions about any line item you do not understand, and confirm whether the rate is locked and for how long. Be cautious if the written estimate does not match what the loan officer discussed with you.
Your goal is not simply to find the lowest advertised rate. It is to choose financing that fits your budget, plans, and comfort level with the lender. Mortgage Rate Utah can be a starting point for exploring Utah mortgage information. For neutral guidance, use the Consumer Financial Protection Bureau’s mortgage comparison resources and review each offer carefully before making a decision.