A home equity line of credit works a lot like a credit card that is secured by your house. A lender sets a credit limit based on your equity, you borrow only what you need, and you pay interest only on the amount you actually use. Because a HELOC is revolving and usually variable, the rate you pay matters more than almost any other feature. This guide explains how HELOC rates work, how to compare current HELOC rates, and how to choose from the best HELOC lenders, including banks, online lenders, and your local HELOC credit union. If you want the basics first, read what a HELOC is and how it works.
How HELOC Interest Rates Are Set
HELOC interest rates are typically variable. Most lenders build them from the prime rate plus a margin, and that margin depends on your credit score, how much equity you have, and how much you want to borrow. Because the rate moves with prime, your minimum payment can change from month to month. That is the biggest difference between a HELOC loan and a traditional fixed-rate installment loan, where the payment stays the same for the whole term.
When you see home equity line of credit interest rates advertised, read the fine print. Some lenders promote a low introductory rate that jumps after a few months, while others quote an ongoing rate from day one. Ask which one you are being shown before you compare offers.
Current HELOC Rates and HELOC Rates Today
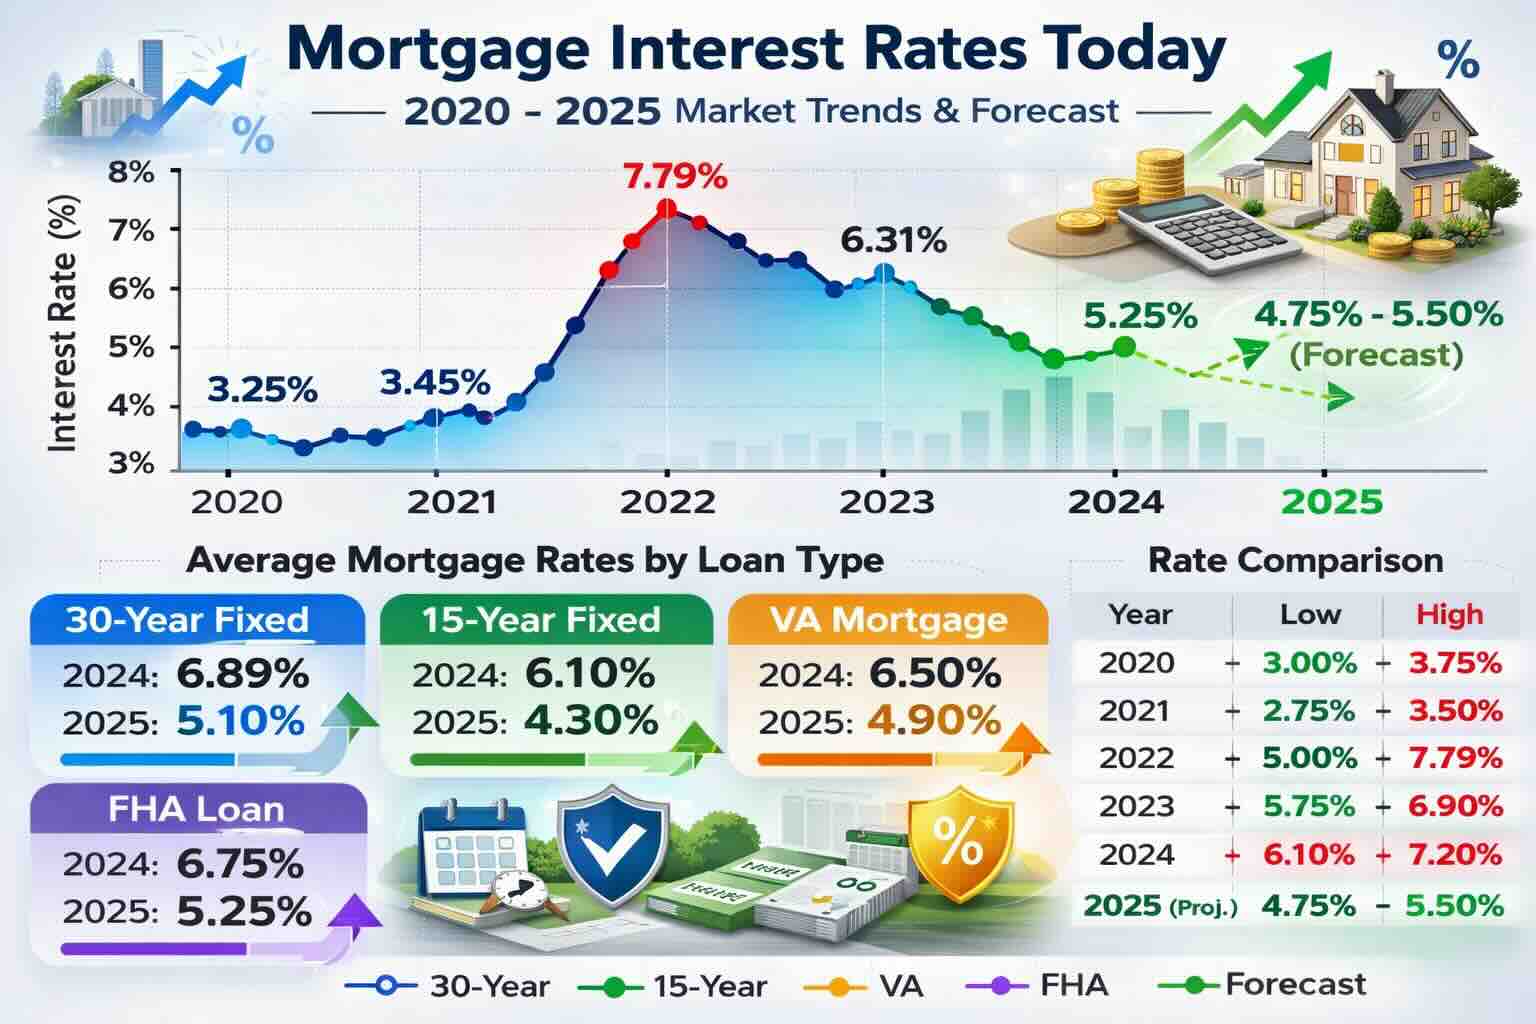
Tracking home equity line of credit rates takes effort because they move constantly, so current HELOC rates you read about in an article may be out of date by next week. Treat any quote for HELOC rates today as a snapshot rather than a promise, and remember that an “as low as” rate is usually reserved for borrowers with strong credit and plenty of equity. Instead of relying on a number in a blog post, check lender websites directly and request a written quote.
When you compare HELOC loan rates from several lenders, look beyond the headline percentage. Ask about the margin over prime, any rate cap, the annual fee, appraisal and closing costs, and whether there is an early-closure penalty. A slightly higher rate with no fees can beat a lower rate that comes with hundreds of dollars in upfront costs.
Best HELOC Rates: What Lenders Look For
The best HELOC rates generally go to borrowers who look low-risk on paper. Most lenders want a credit score in at least the mid-600s, and higher scores earn better pricing. You also typically need more than 15% equity in your home, and many lenders limit total borrowing to roughly 80% to 85% of your home’s value. Steady income, a manageable debt-to-income ratio, and a clean payment history all help you qualify for best HELOC rates rather than the middle of the pack.
Keep in mind that the best HELOC for you is not always the one with the lowest advertised rate. A lender with a longer draw period, a flexible repayment plan, and responsive service may be the better fit for a multi-year project. For a deeper look, see when a HELOC makes sense.
Fixed Rate HELOC and Interest Only HELOC Options
If rate swings make you nervous, ask about a fixed rate HELOC. Some lenders let you convert part of your balance to a fixed rate while the rest of the line stays variable, which gives you predictable payments on money you have already spent. A fixed portion may start at a slightly higher rate than the variable one, so weigh the peace of mind against the cost.
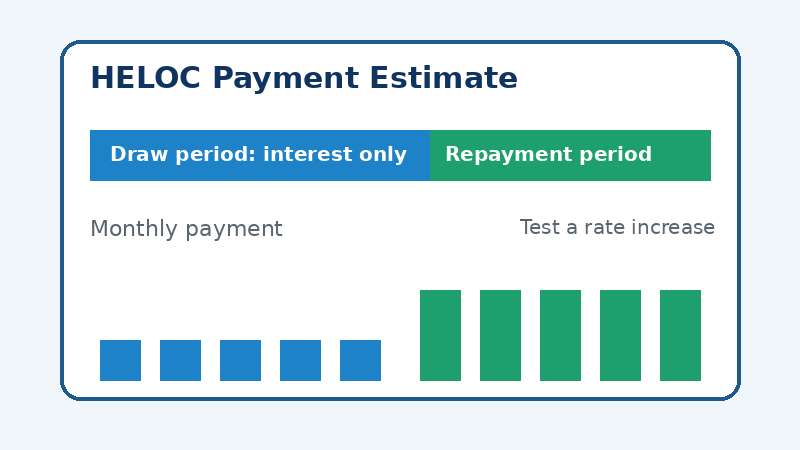
An interest only HELOC is another common structure. During the draw period, which often lasts around ten years, many lenders require only interest payments on what you have borrowed. That keeps early payments low, but the principal is still waiting. When the repayment period begins, typically 10 to 20 years, your payment can rise sharply because you start paying down the balance.
HELOC Calculator Payment Tools to Plan Your Budget
Before you borrow, run the numbers. A HELOC calculator payment tool shows what you would owe during the draw period, and a HELOC calculator free option from a bank or finance site takes only a minute. For a fuller picture, use a HELOC monthly payment calculator to test different balances, and a HELOC repayment calculator to see how your payment changes once the repayment period starts. A home equity line of credit payment calculator lets you stress-test your budget by raising the rate a point or two to see whether you could still afford the payment.
When you are ready to get out of debt, a HELOC payoff calculator shows how extra monthly payments shorten your timeline and cut total interest. Paying even a little principal during the draw period can reduce the shock when repayment begins. You can also compare how a HELOC payment stacks up against a regular mortgage with these Utah mortgage calculators.
How to Choose the Best HELOC Lenders
There is no single winner among HELOC lenders, so compare at least three. Large banks may reward existing customers with rate discounts. Online lenders often move faster, and Bankrate notes that approval typically takes two to six weeks, with some lenders offering much quicker closings. A HELOC credit union may offer lower fees and more personal service, and it is worth including in any comparison. Use this checklist when ranking the best HELOC lenders:
- Margin over prime and any introductory rate period
- Annual fees, appraisal costs, and closing costs
- Draw period and repayment period length
- Fixed-rate conversion options
- Minimum and maximum credit lines
- Customer reviews and servicing quality
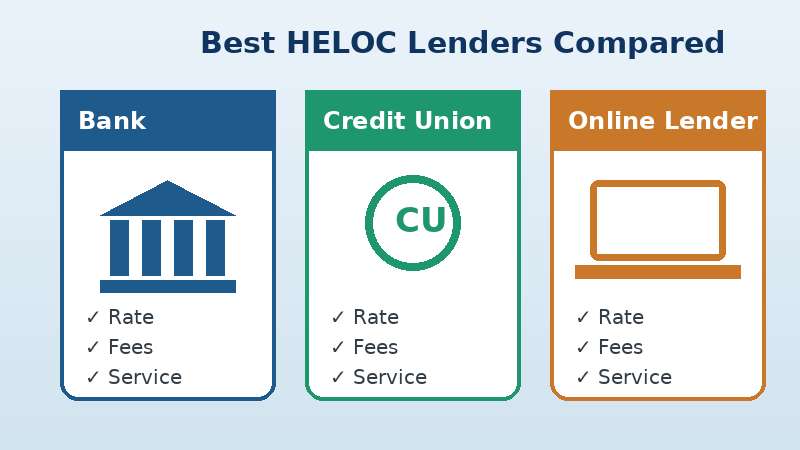
If you want the best home equity line of credit for your situation, rank those factors by what matters most to you, whether that is the lowest rate, the lowest fees, or the most flexibility.
HELOC on Investment Property: Is It Possible?
A HELOC on investment property is harder to find than one on a primary residence. Fewer lenders offer it, and those that do usually require more equity, a higher credit score, and proof of rental income. Rates tend to be higher because lenders see more risk. If you are considering this route, ask each lender up front whether they allow it, because many do not.
Know the Risks Before You Apply
A HELOC is secured by your home, which means you could lose the property if you cannot repay. Applying also triggers a hard credit inquiry, and a variable rate means costs can climb. A HELOC is best for planned expenses such as home improvements, and it is a poor fit for impulse spending. This article is educational and is not financial advice, so talk with a licensed lender or financial advisor about your situation.
Next Steps
Start by checking your equity and credit score, then get quotes from at least three lenders and run each one through a calculator. Understanding HELOC rates before you apply is the surest way to borrow with confidence. Explore more guides on the Mortgage Rate Utah home page.