Understanding Utah mortgage rates is an important part of buying a home, refinancing a current mortgage, or using the equity you have built in your property. Mortgage rates can affect how much you pay each month and how much interest you pay over the life of a loan. Because rates and loan options can vary between borrowers and lenders, it is important to research your options before choosing a mortgage.
Whether you are a first-time homebuyer or an experienced homeowner, comparing rates, estimating your monthly payment, and understanding your credit profile can help you make a more informed decision.
Current Utah Mortgage Rates and 30-Year Mortgage Rates Today
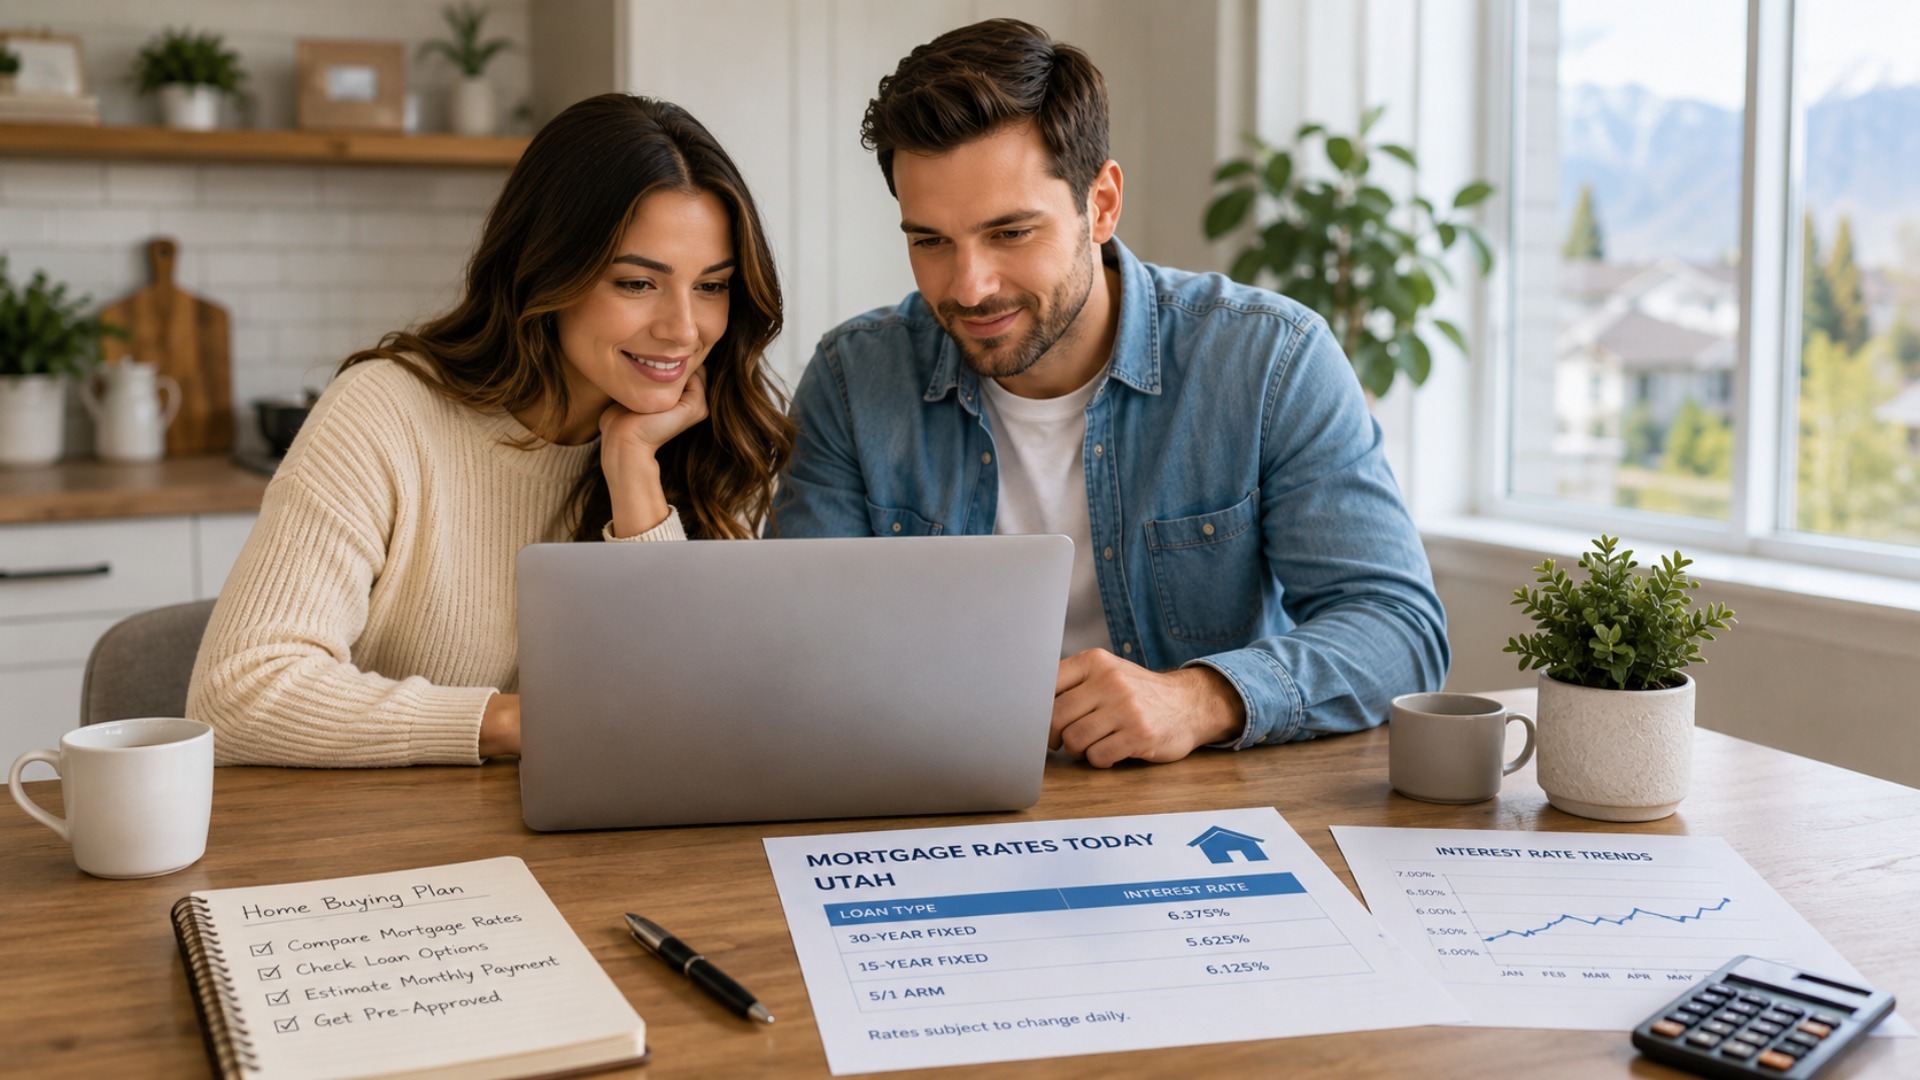
Mortgage rates can change over time based on economic conditions and other factors. When researching mortgage rates Utah, borrowers may find different rates depending on the loan type, lender, loan term, credit score, down payment, and other financial information.
One of the most common loan terms is a 30-year fixed mortgage. People searching for 30 year mortgage rates today, 30 year fixed mortgage rates, and interest rates today 30 year fixed are generally looking for the current cost of financing a home over a 30-year period.
When comparing current 30 year mortgage rates, it is important to look beyond the advertised interest rate. Borrowers should also consider the annual percentage rate, lender fees, closing costs, and other expenses associated with the loan.
Someone searching for the average 30 year mortgage rate today may find different results depending on the source and type of mortgage being considered. Comparing multiple lenders can give borrowers a better understanding of what rates may be available to them.
Other common searches include current 30 year fixed mortgage rates, best 30 year mortgage rates, mortgage rates today 30 year fixed, current interest rates 30 year fixed, and 30 year mortgage interest rates. These terms all relate to the cost of borrowing for a 30-year mortgage, but the actual rate offered to a borrower can vary.
Mortgage Calculator Utah: Estimate Your Monthly Payment
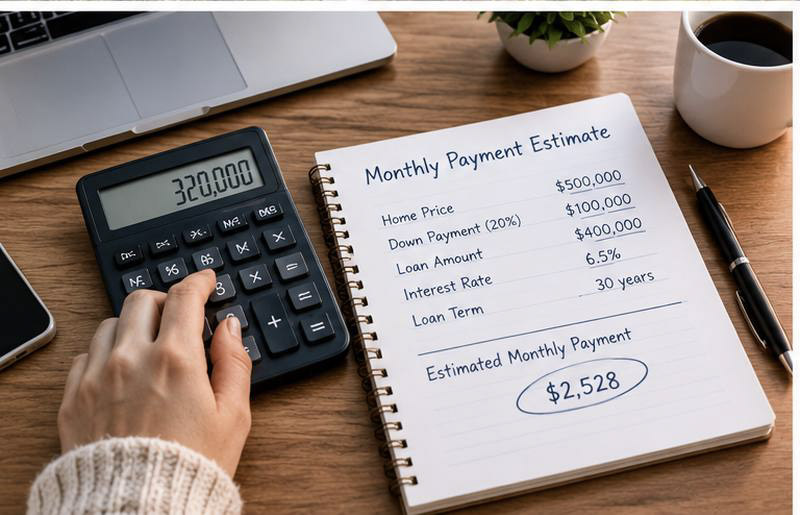
A mortgage calculator can help potential homebuyers understand what a home may cost each month before they apply for a loan. Instead of focusing only on the purchase price, a calculator can help estimate the payment associated with borrowing that amount.
A mortgage calculator Utah can be especially useful for people shopping for homes in the state. By entering information such as the home price, down payment, interest rate, and loan term, buyers can estimate their potential monthly payment.
A mortgage calculator with taxes and insurance can provide an even more complete estimate because property taxes and homeowners insurance can add to the overall monthly housing cost. Buyers can also use a mortgage estimator to compare different home prices and loan amounts.
A mortgage payment calculator can be useful when determining whether a particular home fits within a budget. However, calculator results are only estimates. Actual payments can vary based on the lender, loan terms, property taxes, insurance, mortgage insurance, and other costs.
Using a calculator before speaking with a lender can help buyers establish a realistic price range and better understand their potential financial commitment.
Utah Mortgage Rates by Credit Score
A borrower’s credit profile can have an important effect on the mortgage options they may receive. People researching Utah mortgage rates by credit score should understand that there is not one mortgage rate available to every borrower.
Lenders may consider credit history, income, debt, down payment, loan amount, and other factors when determining eligibility and loan terms. A borrower with a stronger credit profile may receive different terms than someone with a lower credit score.
Borrowers who have experienced credit challenges may search for mortgage lenders for bad credit. Although qualifying for a mortgage may be more difficult with a lower credit score, comparing different lenders and loan programs can help borrowers understand their potential options.
Improving credit before applying for a mortgage may also be worth considering. Paying bills on time, reducing outstanding debt, and reviewing credit reports can help borrowers prepare for the mortgage application process.
Comparing Mortgage Lenders in Utah
Choosing the right mortgage lender is another important part of the home-buying process. Different lenders may offer different interest rates, fees, loan programs, and customer service experiences.
When comparing mortgage lenders Utah, borrowers should look at the complete cost of each loan rather than choosing a lender based only on the advertised interest rate. Comparing best mortgage companies can involve looking at rates, closing costs, loan terms, reputation, and available mortgage products.
Requesting a mortgage quote from multiple lenders can make it easier to compare potential offers. Borrowers may also search for mortgage lenders near me when looking for local lending options.
A local lender may be convenient, but convenience should not be the only consideration. Borrowers should compare the terms of each offer to determine which option best fits their financial situation.
Mortgage Rates Over Time
Mortgage rates do not remain the same forever. People researching mortgage rates over time or mortgage rates over the last 10 years can see how borrowing costs have changed during different economic conditions.
Looking at historical mortgage rates can help put current rates into perspective. However, past performance does not guarantee future rates. Homebuyers should consider whether they can comfortably afford a mortgage based on their current financial situation instead of waiting for a specific rate.
For buyers who are ready to purchase, understanding the current market and comparing multiple loan offers can be more useful than trying to predict exactly where rates will go in the future.
Refinance Rates and 30-Year Fixed Loans
Homeowners who already have a mortgage may also consider refinancing. Refinancing involves replacing an existing mortgage with a new loan, potentially at a different interest rate or with different terms.
Homeowners may research refinance rates 30 year fixed, 30 year refinance rates, and mortgage refinance rates 30 year fixed when determining whether refinancing could make sense.
Other related searches include current home mortgage rates 30 year fixed, 30 year mortgage refinance rates, 30 year refi mortgage rates, and refi rates 30 year fixed.
Before refinancing, homeowners should compare the potential monthly savings with closing costs and other expenses. A lower interest rate does not automatically mean refinancing will save money, especially if the costs of obtaining the new loan are high.
Home Equity Loans and Home Equity Lines of Credit
Homeowners who have built equity in their property may also consider borrowing against that equity. A home equity loan provides a way to borrow money using the home’s equity, while a home equity line of credit allows borrowers to access funds as needed up to an approved limit.
People researching home equity loans Utah, home equity loan interest rates, and home equity line of credit rates may be interested in understanding the costs and requirements associated with these options.
Some homeowners may also search for a home equity line of credit with bad credit. Eligibility and interest rates can vary based on the lender, credit profile, available equity, income, and other factors.
FHA and Other Mortgage Options
Different mortgage programs may be appropriate for different borrowers. For example, some buyers may research an FHA 30 year fixed rate today when considering an FHA loan.
When comparing mortgage options, borrowers should consider more than the interest rate. Down payment requirements, mortgage insurance, closing costs, fees, and other loan requirements can affect the total cost of borrowing.
Making an Informed Utah Mortgage Decision
Whether you are purchasing a home, refinancing, or considering a home equity product, understanding your options can help you make a more informed decision. Start by researching Utah mortgage rates, using a mortgage calculator Utah, and comparing different mortgage lenders Utah.
It can also be helpful to compare 30 year mortgage rates today, review current 30 year mortgage rates, and request a mortgage quote from multiple lenders. If you are concerned about affordability, a mortgage payment calculator can help you estimate potential monthly costs before you begin the application process.
Remember that the mortgage rate is only one part of the total cost of owning a home. Property taxes, homeowners insurance, closing costs, mortgage insurance, maintenance, and other expenses should also be considered.