How Much Income Do I Need to Buy a House in Utah? (2026 Guide)
Buying a home is an exciting milestone, but figuring out whether you can afford one can be confusing. One of the biggest questions future homeowners ask is, how much income do I need to buy a house? The answer depends on several factors, including your salary, existing debt, credit score, down payment, and current mortgage rates.
For people looking to buy a home in Utah, these factors matter even more because home prices vary significantly by city and neighborhood. Whether you’re purchasing your first home or looking to upgrade, knowing how mortgage lenders evaluate your finances can help you make a more informed decision.
This guide explains how much income you may need, how lenders calculate mortgage affordability, and what steps you can take to improve your chances of qualifying.
How Much Mortgage Can I Afford Based on My Income?
One of the first things you should determine before shopping for a home is how much mortgage you can afford based on your current salary.
Mortgage lenders typically look at your gross monthly income, the amount you earn before taxes, and compare it with your existing financial obligations. This helps them estimate how much you can reasonably spend on a mortgage payment.
A common budgeting guideline is to keep monthly housing expenses around 28% of your gross income. However, this isn’t a strict requirement for every mortgage program.
For example, if you earn $75,000 annually, your gross monthly income is approximately $6,250. Using the 28% guideline, you might aim to spend around $1,750 per month on housing.
Keep in mind that your housing expenses include more than just your mortgage payment. Property taxes, homeowners insurance, mortgage insurance, and HOA fees may also need to be included.
If you’re wondering how much monthly income you need for a mortgage, remember that lenders will also consider your existing debt payments.
How Much Can I Borrow for a Mortgage?
Another important question homebuyers ask is: How much can I borrow for a mortgage?
The amount a lender is willing to approve depends on your income, debt, credit history, down payment, and the mortgage program you’re applying for.
For example, two people earning the same salary might qualify for completely different mortgage amounts. Someone with minimal debt and a strong credit score may qualify for a larger loan than someone with high credit card balances and multiple car payments.
This is why answering the question: How much will a bank lend me for a house requires looking at your entire financial situation rather than just your salary.
Using a mortgage affordability calculator can help you estimate your purchasing power. These calculators allow you to enter your income, debts, down payment, and estimated interest rate to determine an approximate home price range. However, qualifying for a mortgage doesn’t necessarily mean you should borrow the maximum amount available. It’s important to choose a monthly payment that fits comfortably within your personal budget
How Much Income Is Needed for a Mortgage in Utah?
There is no single minimum income required to purchase a home in Utah. The income needed for mortgage approval depends largely on the home’s price, your monthly debts, and the interest rate you receive.
For example, someone purchasing a $300,000 home will generally need less income than someone purchasing a $500,000 home, assuming similar financial circumstances.
The table below shows how different home prices affect estimated mortgage payments.
| Home Price | 5% Down Payment | Monthly Principal & Interest |
| $300,000 | $15,000 | $1,801 |
| $400,000 | $20,000 | $2,402 |
| $500,000 | $25,000 | $3,002 |
These estimates assume a hypothetical 6.5% interest rate on a 30-year fixed mortgage. They exclude property taxes, insurance, mortgage insurance, and HOA fees. Actual rates and payments vary.
When determining the minimum income to buy a house, remember that these payments represent only part of your total monthly housing expenses. Your income requirements also depend on existing debts and the money available for a down payment.
What Debt-to-Income Ratio Is Needed for a Mortgage?
Your debt-to-income ratio, also known as DTI, is one of the most important factors lenders evaluate when reviewing mortgage applications.
The debt-to-income ratio for mortgage approval measures the percentage of your gross monthly income that goes toward monthly debt payments.
For example, if you earn $5,000 per month and have $1,500 in total monthly debt payments, including your proposed housing payment, your DTI would be 30%.
Many borrowers wonder what debt-to-income ratio is needed for a mortgage. Although requirements vary, a DTI of 43% or lower is a common reference point. Some mortgage programs allow higher ratios depending on your credit score, financial reserves, and other qualifications.
If you’re wondering how much debt you can have and still buy a house, reducing outstanding credit card balances and other monthly obligations may help you qualify for a larger mortgage.
What Is the Minimum Credit Score for Mortgage Approval?
Your credit score plays an important role in determining whether you qualify for a mortgage and what interest rate you might receive.
The minimum credit score for mortgage approval depends on the loan program and lender.
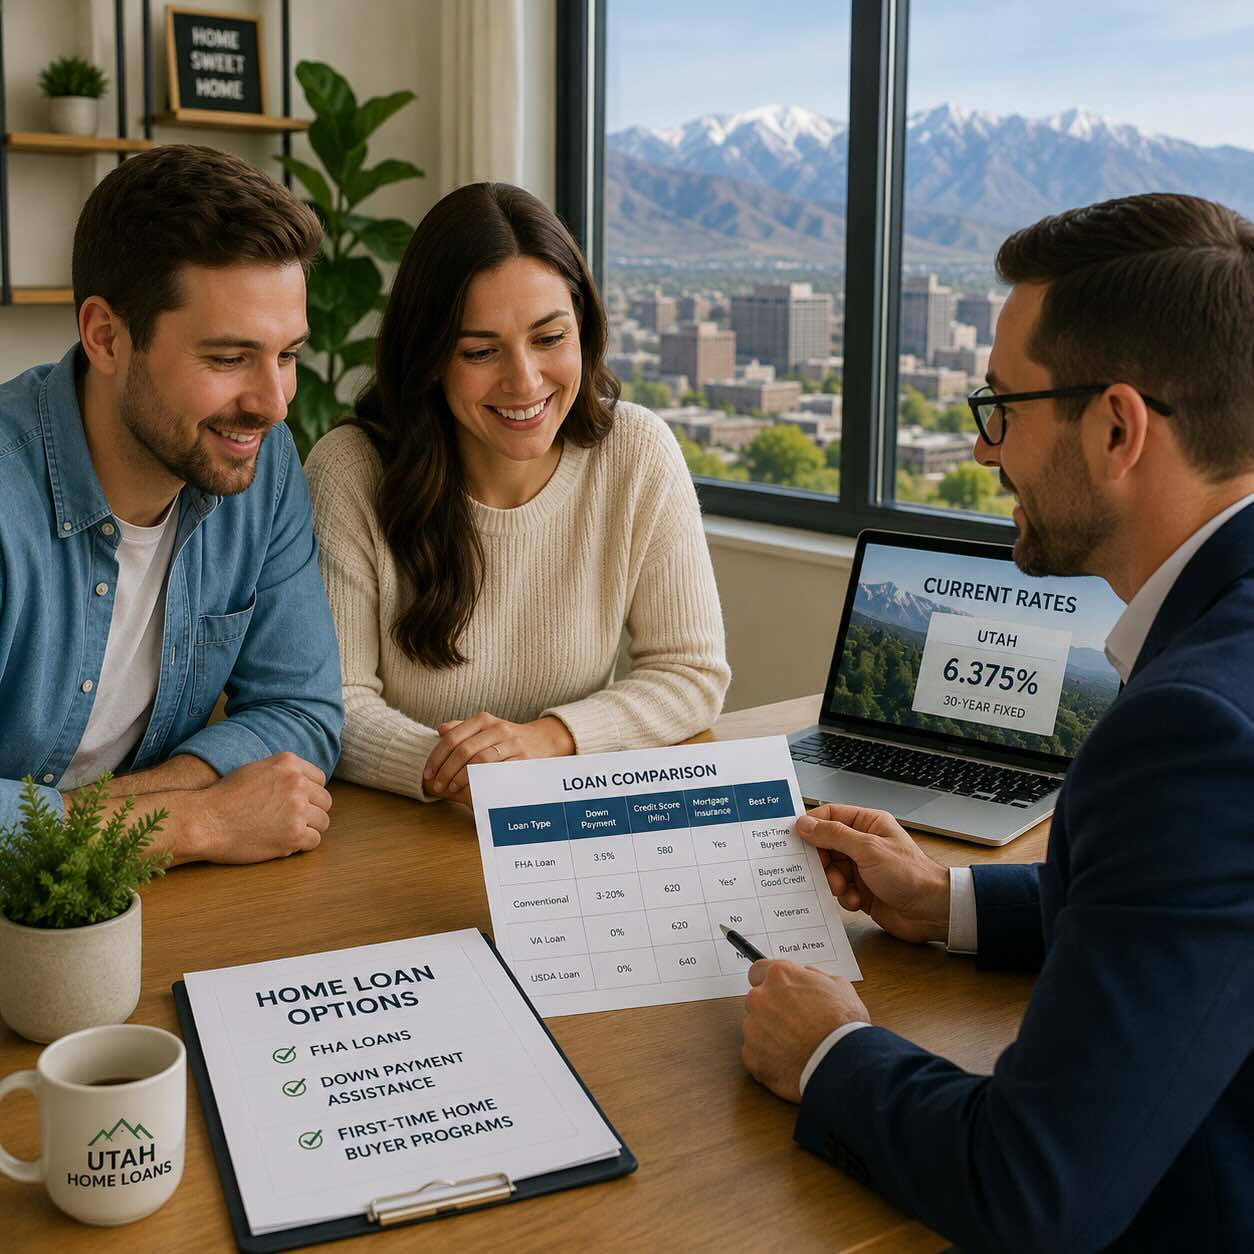
For example, the credit score needed for FHA loan approval can be as low as 580 with a 3.5% down payment under FHA guidelines. Some borrowers with lower scores may qualify with larger down payments, although individual lenders may have stricter requirements.
The credit score needed for conventional loan approval varies by loan program. While a score of 620 is a common benchmark, some programs use different eligibility standards.
Improving your credit score before applying for a mortgage could help you qualify for better loan terms and potentially reduce your monthly payment.
How Much Down Payment Do You Need for a House?
One of the biggest misconceptions about purchasing a home is that you need a 20% down payment.
The minimum down payment for a house depends on the type of mortgage you choose.
Some conventional loan programs allow down payments as low as 3%, while eligible FHA borrowers may qualify with a 3.5% down payment.
If you’re wondering, can I buy a house with no down payment? Certain VA and USDA loan programs offer zero-down-payment options for eligible borrowers.
However, your down payment isn’t the only expense you should prepare for.
When considering how much money you should save before buying a house, you should also account for closing costs, moving expenses, repairs, and emergency savings.
Saving additional money before purchasing a home can help you manage unexpected expenses after moving in.
What Do I Need to Get Pre-Approved for a Mortgage?
Getting pre-approved is an important step in the homebuying process because it helps you understand how much a lender may be willing to loan you.
Common mortgage pre-approval requirements include proof of income, employment history, credit information, bank statements, and documentation of existing debts.
If you’re wondering what you need to get pre-approved for a mortgage, start by gathering recent pay stubs, W-2 forms, bank statements, and identification.
Self-employed borrowers may need to provide additional financial documentation.
Another common question is: How long does mortgage pre-approval last? Most pre-approval letters remain valid for approximately 60 to 90 days, although this depends on the lender.
Some borrowers also wonder, does mortgage pre-approval hurt your credit? A lender may perform a hard credit inquiry, which can temporarily affect your credit score. However, mortgage inquiries made within a designated rate-shopping period are generally treated as a single inquiry by credit scoring models.
Common First-Time Home Buyer Mistakes to Avoid
Understanding common first-time home buyer mistakes can help you avoid unnecessary financial stress.
One mistake is assuming that the maximum mortgage amount you’re approved for is automatically the amount you should spend.
Other mistakes include failing to budget for closing costs, overlooking property taxes and insurance, and taking on additional debt before closing on a home.
Another mistake is not comparing mortgage rates between lenders. Even a small difference in interest rates can significantly affect how much you pay over the life of your mortgage.
If you’re looking for ways to reduce your expenses, understanding how to lower your mortgage payment is a good place to start.
Improving your credit score, making a larger down payment, shopping for competitive mortgage rates, or purchasing a less expensive home can all help reduce your monthly payment.
Final Thoughts: How Much Income Do You Really Need to Buy a House?
Determining how much income you need to buy a house in Utah involves more than looking at your annual salary.
Your debt-to-income ratio, credit score, down payment, and mortgage interest rate all influence how much you can afford.
Before beginning your home search, consider using a mortgage calculator, reviewing your finances, and speaking with a mortgage professional who understands the Utah housing market.
You can also explore additional mortgage information and resources at Mortgage Rate Utah.
For more guidance, visit the Consumer Financial Protection Bureau homebuying resources.
The most important thing to remember is that qualifying for a mortgage and comfortably affording a home aren’t always the same thing. Finding a home that fits your budget can help you build long-term financial stability while enjoying the benefits of homeownership.