Buying a home is an important financial decision, and understanding how much you can afford is one of the first steps toward homeownership. For Utah homebuyers, the total cost of owning a home includes more than the purchase price. Monthly mortgage payments, property taxes, homeowners insurance, existing debts, and interest rates can all affect your budget. Before choosing a property, it is helpful to estimate your monthly expenses and compare different financing options.
A mortgage calculator with taxes can help you estimate your potential monthly housing costs. By comparing mortgage interest rates today, using a dti calculator, and reviewing available loan programs, you can make a more informed decision about your home-buying budget. This guide explains how to use these tools and prepare to apply for a mortgage.
Understanding Mortgage Calculators and Monthly Payments
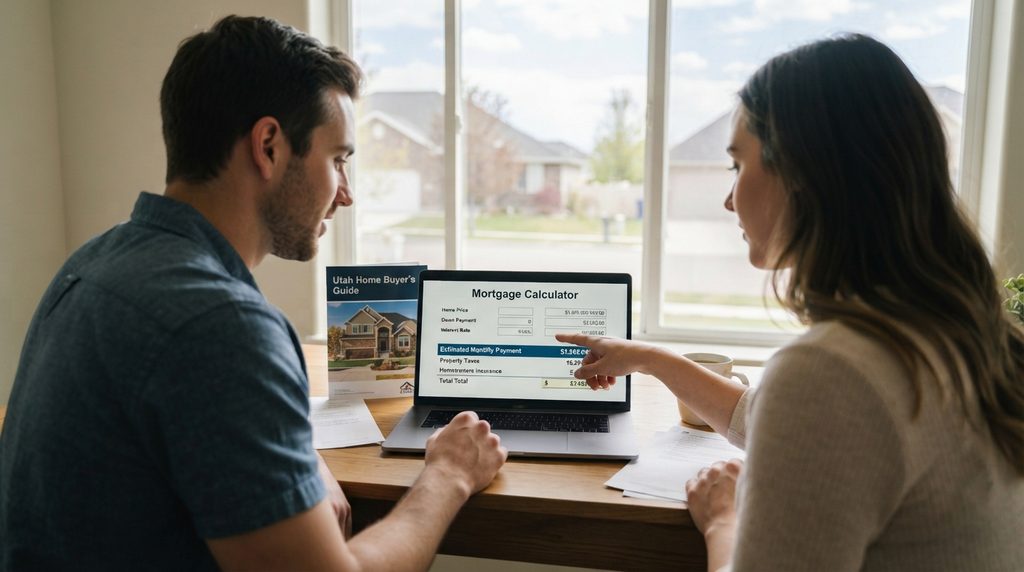
mortgage calculator helps estimate the monthly principal and interest payment on a home loan. More detailed calculators can also include property taxes, homeowners insurance, mortgage insurance, and homeowners association fees. These additional expenses are important because they can significantly affect the total amount you pay each month.
A mortgage calculator with taxes is useful when comparing homes with different prices or tax costs. You can change the purchase price, down payment, interest rate, and loan term to see how each factor affects your estimated payment. A basic mtg calculator can provide a starting point, but make sure you understand which expenses are included in its results. For example, a home with a lower purchase price may not always have a lower monthly cost if property taxes, insurance, or HOA fees are higher. You should also budget for repairs, maintenance, and unexpected expenses. Calculator results are estimates rather than guaranteed loan offers, so confirm the actual terms with a mortgage lender
Comparing Current Mortgage Interest Rates
Interest rates are an important part of the home-buying process because they affect your monthly payment and the total interest paid over time. Researching mortgage interest rates today and current mortgage interest rates can help you understand the options available from different lenders.
Many borrowers compare 30 year mortgage rates because a 30-year mortgage spreads payments over a longer period. This can make monthly principal and interest payments more manageable than those of a shorter-term loan. However, a longer repayment period can result in more total interest over the life of the mortgage.
You may also encounter searches for current home interest rates, current home loan interest rates, and current home mortgage rates. These phrases relate to the same general goal: finding financing for a home purchase. Actual rates depend on factors such as credit history, down payment, loan type, loan amount, and lender requirements.
When comparing offers, consider the annual percentage rate (APR), closing costs, and loan terms in addition to the advertised interest rate. Rates can change, so verify current offers directly with lenders before making a decision.
Using a DTI Calculator to Understand Affordability
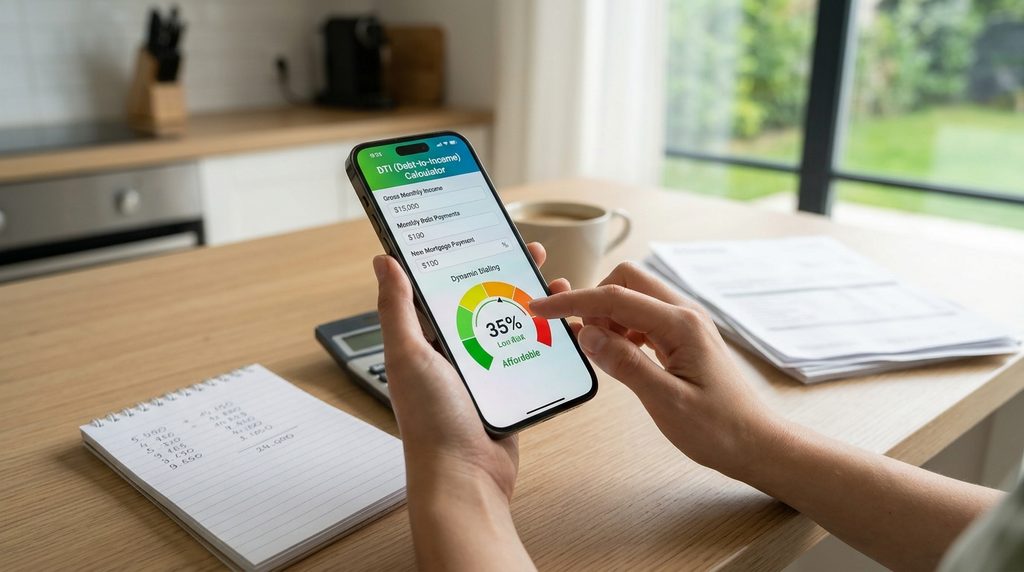
Your debt-to-income ratio, commonly called DTI, compares your monthly debt payments with your gross monthly income. Lenders often consider this ratio when deciding whether a borrower qualifies for a mortgage.
A dti calculator can help you estimate your ratio before applying for a loan. Include your recurring monthly debt payments, such as car loans, student loans, credit card minimum payments, and other applicable obligations. Then consider how a potential mortgage payment would change your total debt obligations.
For example, suppose your gross monthly income is $6,000. If your monthly debts, including your estimated mortgage payment, total $2,100, your estimated DTI is 35%. This is an illustration, not a guarantee of mortgage approval. Lenders may apply different requirements depending on the loan program and your overall financial situation.
If your estimated DTI is higher than expected, you may want to consider reducing certain debts, increasing your savings, or looking at homes with lower monthly costs. Reviewing your budget before applying can help you understand what payment may be comfortable for you.
Comparing Mortgage Providers and Credit Union Rates
After estimating your budget, compare several mortgage providers before choosing a lender. Banks, credit unions, and mortgage companies may offer different loan products, interest rates, fees, and qualification requirements.
Researching credit union mortgage rates alongside other available offers can help you understand your choices. Some credit unions require membership, and their products and eligibility rules can vary. Compare written loan estimates whenever possible so you can review interest rates, APRs, estimated payments, closing costs, and other fees consistently.
You may also want to research usaa mortgage rates if you are considering USAA or another specific provider. Check the lender’s current offerings, eligibility requirements, and terms directly rather than assuming that one lender will always have the best rate.
The goal is to find a loan that fits your financial situation and long-term plans. A slightly lower interest rate may not necessarily produce the best overall deal if the loan includes higher fees or terms that do not fit your needs.
Exploring VA Home Loans and VA Calculators
Eligible veterans, active-duty service members, and certain surviving spouses may qualify for home loans backed by the U.S. Department of Veterans Affairs. VA-backed loans can offer benefits to eligible borrowers, including the possibility of purchasing a home without a down payment in many cases. Eligibility and lender requirements still apply, and some borrowers may need to pay a VA funding fee.
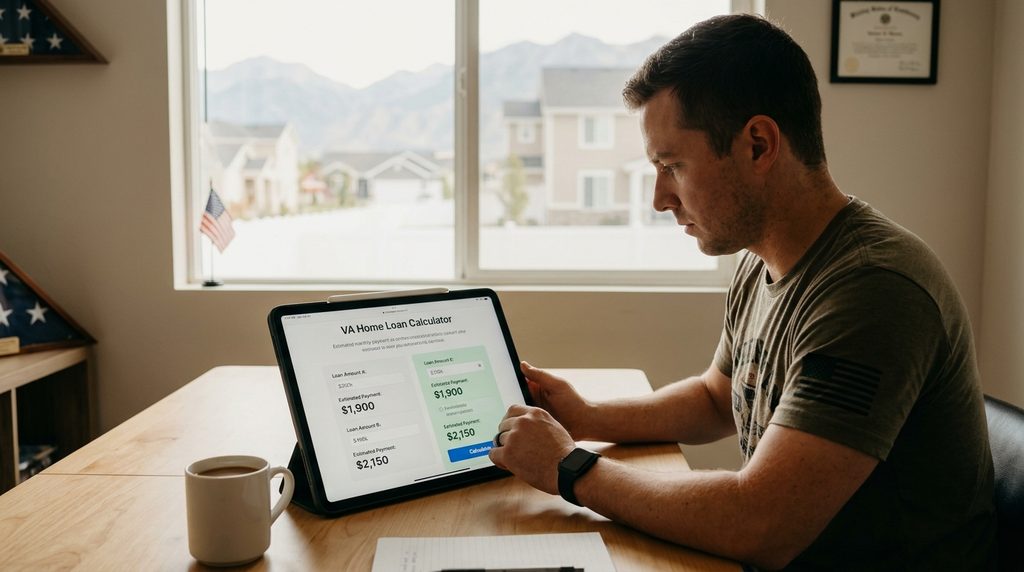
A va loan calculator can help estimate potential monthly payments based on a home’s price, loan amount, interest rate, and loan term. A va home loan calculator or va loan payment calculator may also help you compare different financing scenarios before speaking with a lender.
People searching for a va home loan should review their eligibility and understand the full costs of borrowing. Taxes, homeowners insurance, closing costs, and applicable fees can affect the total expense. Compare loan terms carefully rather than relying on a calculator’s estimated payment alone.
For official information about eligibility and VA-backed home loans, visit the U.S. Department of Veterans Affairs: https://www.va.gov/housing-assistance/home-loans/.
Understanding Home Equity Loans and HELOC Rates
Homeowners who already own property may build equity as they repay their mortgage or as their property’s value changes. House equity, more commonly called home equity, is the difference between a property’s current market value and the outstanding debt secured by it.
A home equity loan generally allows a homeowner to borrow against available equity and receive the money as a lump sum. A home equity line of credit, commonly called a HELOC, usually provides a revolving credit line that can be used as needed, subject to the lender’s terms.
When researching heloc rates and heloc loan rates, compare interest rates, fees, draw periods, and repayment requirements. A home equity line may offer flexibility, but its interest rate may be variable, meaning payments can increase. Borrowing against your home also carries risks if you cannot repay the debt.
These products serve a different purpose from a mortgage used to purchase a home. Before choosing a home equity loan or HELOC, review the costs and risks and make sure the repayment terms fit your budget.
Refinancing and Preparing to Apply for a Home Loan
Homeowners sometimes consider refinancing to change their interest rate, monthly payment, or loan term. Researching refi mortgage rates can help you determine whether refinancing may be worth considering. However, a lower interest rate does not automatically mean refinancing will save money. Closing costs, the remaining loan balance, and the length of the new loan all matter.
For buyers preparing to apply for house loan financing, organizing financial documents is an important step. Lenders may ask for income records, bank statements, employment information, credit details, and information about existing debts.
You can also research how to prequalify for mortgage loan options. Prequalification may provide an early estimate of how much you could borrow based on information you provide. It is not the same as final loan approval, and each lender may use a different process.
Some people search online for prequalify for morgage loan. Regardless of the wording used, review the lender’s requirements and ask whether the process involves a credit inquiry. Preparing your documents, checking your credit history, and reviewing your monthly budget can help you approach the application process more confidently.
Make an Informed Home-Buying Decision
Choosing a home requires more than finding the lowest advertised interest rate. Utah homebuyers should estimate their full monthly housing costs, review their debt-to-income ratio, and compare financing options from several lenders.
A mortgage calculator with taxes can help you understand possible payments, while a DTI calculator can help you assess your current debt obligations. Comparing conventional mortgages, VA-backed loans, and other financing options may help you identify a loan that fits your circumstances.
Before making a final decision, verify current rates, review loan estimates, and ask questions about fees and repayment terms. Careful planning can help you understand the financial responsibilities of homeownership and make a more informed choice.
Ready to take the next step?