Buying a home is a major financial decision, and choosing the right mortgage can make a significant difference in your long-term budget. With so many mortgage lenders, loan programs, and interest rates to consider, it is important to understand your options before committing to a loan. Whether you are purchasing your first home, upgrading to a larger property, or exploring refinancing, researching mortgage rates today and comparing lenders can help you make a more informed decision.
A mortgage loan allows you to purchase a property by borrowing money from a lender and repaying the balance over time, typically with interest. Understanding the different types of loans, the approval process, and the costs involved can help you find financing that fits your financial situation.\
Compare Mortgage Rates Today
One of the first steps when shopping for a home loan is researching current interest rates. Mortgage interest rates today can influence your monthly payment and the total amount you pay over the life of your loan. Rates may vary based on the lender, loan type, credit history, down payment, loan term, and broader economic conditions.
When comparing mortgage rates today, remember that the lowest advertised rate does not always mean the lowest overall cost. Some loans may include discount points, origination fees, or other expenses that affect how much you pay at closing. Requesting estimates from multiple mortgage companies can help you compare interest rates, fees, and loan terms more accurately.
For additional information about mortgage costs and the home-buying process, visit the Consumer Financial Protection Bureau’s home-buying resources:
External link: https://www.consumerfinance.gov/owning-a-home/
How to Find the Best Mortgage Lenders
Choosing among the best mortgage lenders involves more than comparing interest rates. You should also consider customer service, loan options, application requirements, closing costs, and how clearly the lender explains your financing choices. Some mortgage lenders specialize in first-time homebuyers, while others offer programs for veterans, refinancing, or borrowers with specific financial needs.
Searching for mortgage lenders near me can help you identify local providers who understand the housing market in your area. However, online mortgage companies may also offer competitive options, convenient application processes, and access to different loan programs.
Before choosing a lender, compare several offers and ask questions about fees, rate-lock periods, estimated closing costs, and required documentation. Reading customer reviews and checking lender credentials can also help you evaluate your options. Taking time to compare providers may help you find a mortgage that fits both your budget and your long-term goals.
Why Home Loan Pre-Approval Matters
Getting a home loan pre-approval is an important step before you begin seriously shopping for a house. During the pre-approval process, a lender reviews information about your income, debts, credit history, and finances to estimate how much you may be able to borrow.
A mortgage pre-approval can help you understand your potential price range and demonstrate to sellers that you have started the financing process. However, pre-approval is not a guarantee of final loan approval. Your lender will still need to verify your information and evaluate the property before the mortgage can close.
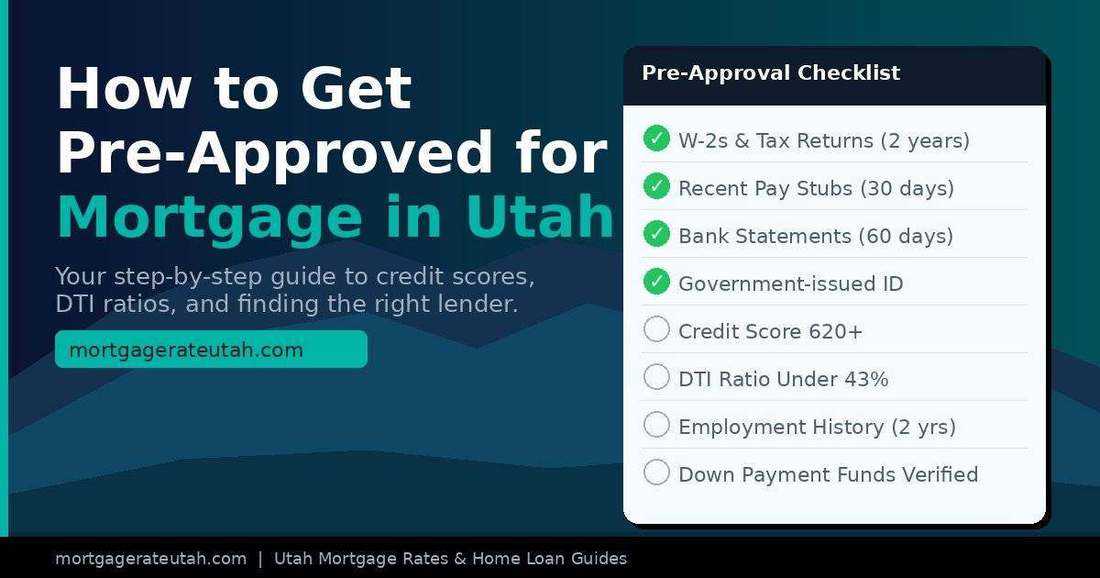
If you are wondering how to get preapproved for a mortgage, start by gathering documents such as pay stubs, tax records, bank statements, and information about your existing debts. Then, contact one or more lenders to understand their requirements.
The terms mortgage pre-approval and mortgage preapproval are often used interchangeably. Regardless of the spelling, the goal is the same: to help you understand your borrowing options before making an offer on a home.
Explore VA Loans and Current VA Mortgage Rates
Eligible veterans, active-duty service members, and certain surviving spouses may qualify for home financing through the VA home loan program. VA loans can offer benefits such as no required down payment in many cases and no private mortgage insurance requirement, although borrowers may still face other costs and eligibility requirements.
When comparing current VA mortgage rates, remember that rates and loan terms can vary by lender and borrower. Comparing multiple providers can help you understand the options available to you.
Researching the best VA loan lenders means looking for lenders experienced with VA financing who can explain eligibility, funding fees, closing costs, and the documentation you may need. Ask each lender for a detailed loan estimate so you can compare offers based on more than the advertised rate.
For official eligibility and program information, visit the U.S. Department of Veterans Affairs:
External link: https://www.va.gov/housing-assistance/home-loans/
Use a Simple Mortgage Calculator to Estimate Payments
Before deciding how much house you can afford, estimate your potential monthly mortgage payment. A simple mortgage calculator can help you understand how the loan amount, interest rate, and repayment term affect your payment.
For example, a larger down payment may reduce the amount you need to borrow, while a lower interest rate may reduce the interest you pay over time. Comparing different scenarios can help you see how a change in loan terms could affect your budget.
A mortgage affordability calculator can provide a broader estimate of what you may be able to afford based on your income, recurring debts, down payment, and estimated housing expenses. Remember that the total cost of owning a home may also include property taxes, homeowners insurance, mortgage insurance when applicable, utilities, maintenance, and homeowners association fees.
Calculators provide estimates rather than guarantees. Use them as a starting point, then review your budget and confirm the actual numbers with a lender.
Understanding Mortgage Refinancing
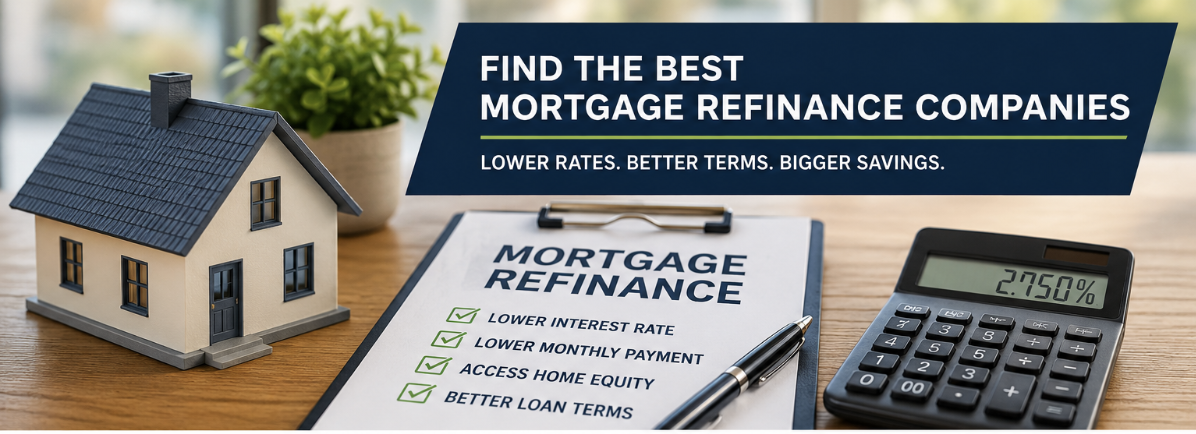
If you already own a home, mortgage refinancing may be worth exploring. Refinancing replaces your existing mortgage with a new loan, potentially allowing you to change your interest rate, repayment term, or loan structure.
Homeowners may consider refinancing to reduce their monthly payment, move from an adjustable-rate mortgage to a fixed-rate loan, or change the length of their repayment period. However, refinancing usually involves closing costs, and a lower monthly payment does not automatically mean lower total costs.
Before deciding to refinance a home loan, compare your current mortgage terms with the proposed new loan. Consider how long you plan to stay in the property, the costs of refinancing, and the time it may take for potential savings to offset those expenses.
Some homeowners also investigate cash out refinance rates when they want to borrow against available home equity. A cash-out refinance replaces the existing mortgage with a larger loan and allows the homeowner to receive part of the difference in cash, subject to lender requirements and available equity. Because this increases the amount borrowed against the home, it is important to consider the long-term financial impact.
When Should You Consider a Second Mortgage?
A second mortgage is another loan secured by your home while your original mortgage remains in place. A 2nd mortgage may allow eligible homeowners to access some of their home equity for expenses such as renovations or other major costs.
Second mortgages can take different forms, including home equity loans and home equity lines of credit. The right option depends on how you want to access the funds, the repayment terms, and the costs involved.
Before taking out a second mortgage, review the interest rate, payment schedule, fees, and risks. Since the loan is secured by your property, failing to make payments could put your home at risk. Compare alternatives carefully and make sure the additional debt fits your budget.
Choose a Mortgage That Fits Your Financial Goals
Finding the right mortgage starts with understanding your finances and comparing available options. Research mortgage rates today, evaluate the best mortgage lenders for your situation, and complete the home loan pre-approval process before making major purchasing decisions.
Whether you are exploring VA financing, estimating payments with a mortgage affordability calculator, or comparing mortgage refinancing options, take the time to understand the costs and terms. A well-informed decision can help you choose a mortgage that supports your budget and long-term homeownership goals.